Dear traders, dear stock market friends.
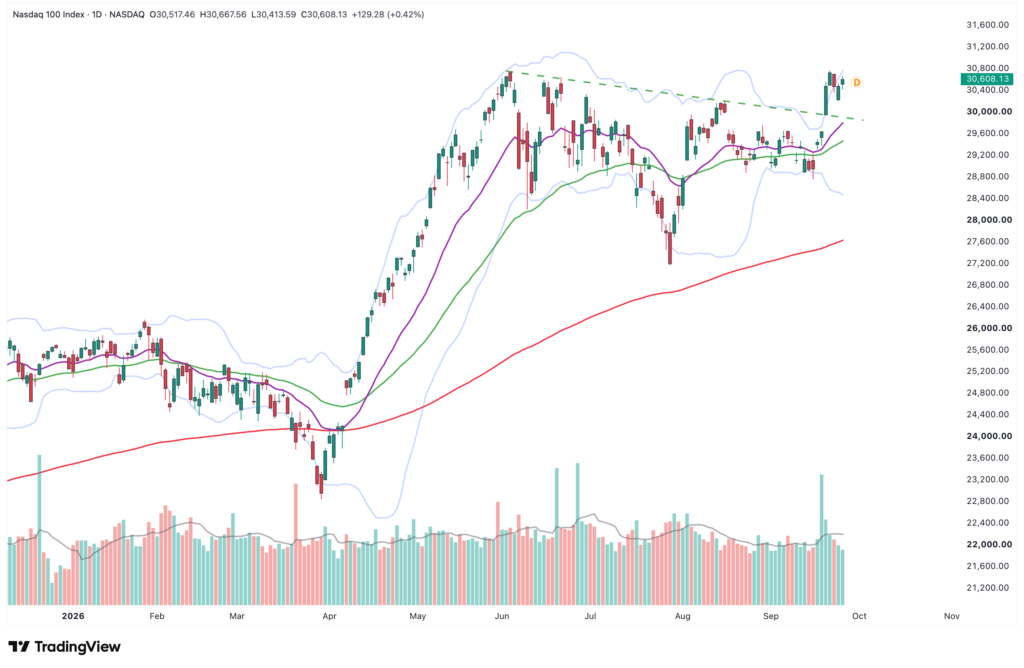
With a weekly gain of 3.25 percent, the Nasdaq 100 was significantly stronger in the last trading week than the S&P 500 and the Dow Jones. While the S&P 500 only gained around 1.2 percent and the Dow Jones even slightly declined, the Nasdaq 100 was driven upwards by a new wave of AI euphoria in particular.
Among other things, the strong launch of Meta’s new AI agent Muse was the trigger. The application not only led to strong price gains for Meta itself, but also fueled hopes for continued growing demand for computing power. This benefited semiconductor stocks in particular. At the same time, rising bond yields and continued high oil prices weighed on the overall market.
What is noteworthy is that the Nasdaq 100 was able to largely ignore these factors and even marked a new all-time high on Tuesday.
Meta and semiconductor stocks benefit from renewed AI euphoria
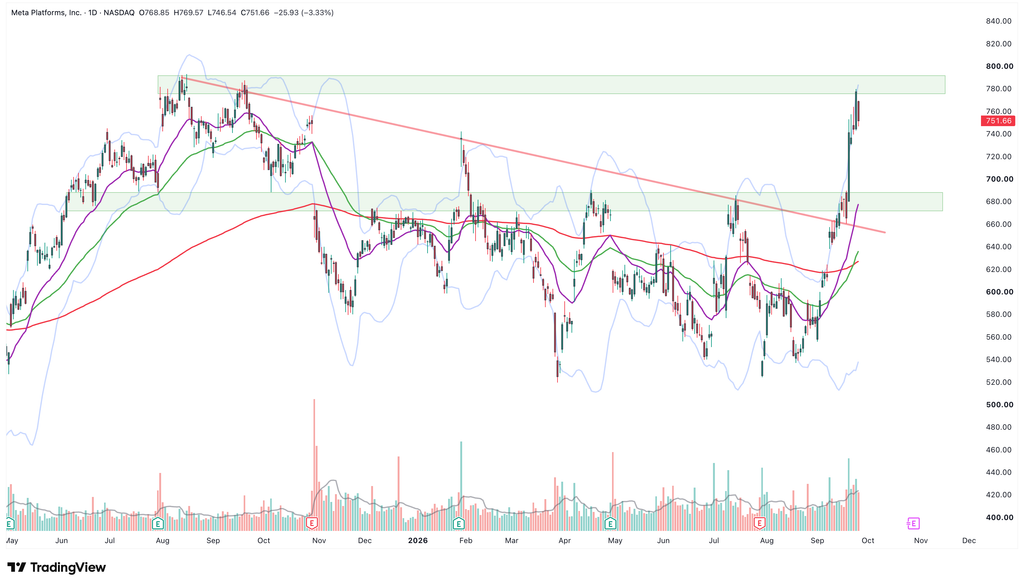
The decisive impetus came as early as the start of the week. Meta rose by more than 11 percent on Monday. The AI agent Muse, which had already reached the top of the US app store at the beginning of September, had reached the top of the US app store over the weekend, while new usage and download data indicated surprisingly strong demand. Wells Fargo provided additional momentum with a significant increase in the price target for Meta shares. This strong response to Muse fueled hopes that Meta’s high AI investments could increasingly be reflected in commercially successful products.
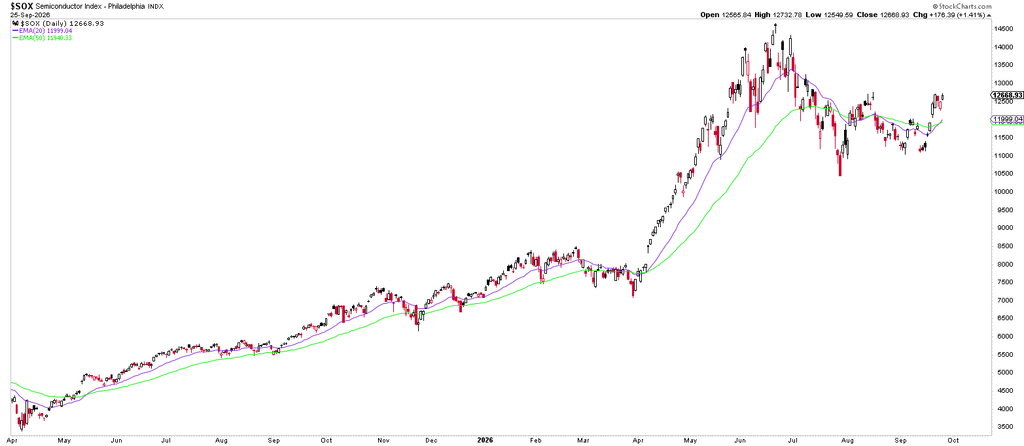
The positive sentiment immediately spread to the semiconductor sector: AMD gained around 10 percent, Intel about 12 percent, and Arm about 17 percent. The Philadelphia Semiconductor Index alone rose by more than 4 percent on Monday alone.
This also explains why the Nasdaq 100 has performed significantly better than the S&P 500 and the Dow Jones. It is precisely the companies that have benefited from the new AI craze that have a particularly high weight in the Nasdaq 100. The S&P 500 is more broadly distributed across different sectors, while the Dow Jones has benefited even less from the rally in large semiconductor and technology stocks.
In addition, on Friday, new Copilot features from Microsoft and an $11.6 billion cloud contract between Anthropic and Akamai generated further positive headlines around AI and the infrastructure required for it.
Rising yields become a test of endurance
The relative strength of the Nasdaq 100 was all the more striking because the interest rate environment deteriorated significantly starting Wednesday. The preliminary US Composite PMI for September jumped to 58.4 points, its highest level since July 2021. The surprisingly robust economic performance reinforced expectations that the US central bank could further tighten monetary policy.
The yield on ten-year US government bonds rose to its highest level since 2007. This is fundamentally a burden for high-rated growth companies, as rising interest rates reduce the attractiveness of future corporate earnings compared to safe bonds.
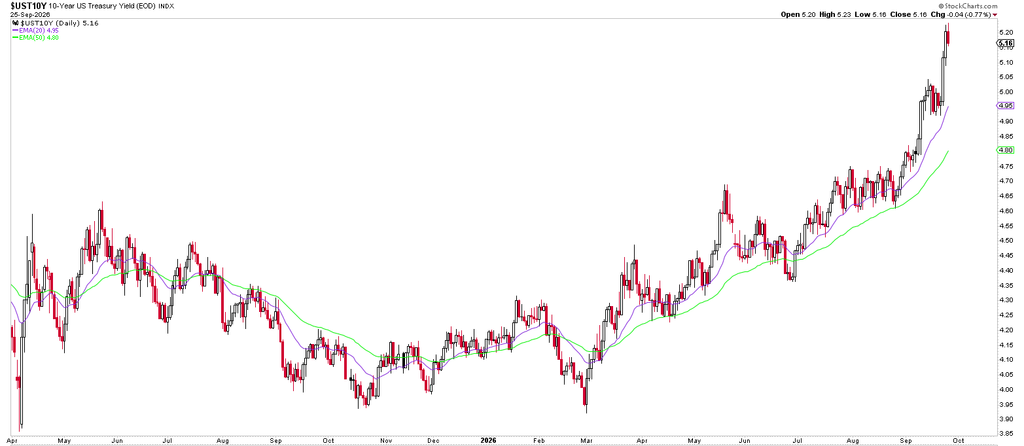
The Nasdaq 100 did fall on Wednesday, but it largely managed to defend the strong gains from the beginning of the week. This shows that the AI euphoria is currently strong enough to at least partially compensate for significant headwinds from the bond market.
Nasdaq 100 defends its break to a new all-time high
Charttechnically, the week thus leaves a positive picture for the time being. On Tuesday, the Nasdaq 100 rose to 30,770 points, reaching a new record high. At the end of the week, with around 30,608 points, the index was only a few points below that level.
In the short term, therefore, the question is primarily whether the index can hold above the psychologically important mark of 30,000 points. As long as this is achieved, the most recent breakout remains intact and a renewed attack on the weekly high is possible.
A rebound below 30,000 points, on the other hand, would be a first warning sign. The area around 29,600 to 29,650 points is coming into focus, near which the Nasdaq 100 had ended the previous trading week.
PCE, the labor market, and Micron in focus
The upcoming trading week could already show how resilient the recent tech rally actually is. On Wednesday, PCE inflation data for August will be released in the US. After the strong rise in bond yields, the market is likely to react particularly sensitively to any surprises in inflation.
On the same day, Micron Technology will also release its quarterly results. Following the strong performance of semiconductor stocks, attention is likely to be focused on statements regarding demand for memory chips for AI data centers.
The US labor market report for September will follow on Friday, rounding off the week. Strong data could further underpin expectations of further interest rate hikes, thus putting further pressure on the bond market.
This brings two opposing forces together for the Nasdaq 100: on the one hand, a continued strong AI story, and on the other hand, an increasingly restrictive interest rate environment. Which side prevails will be crucial to determining whether the recent surge above the 30,000 point mark will hold.
Author: Tobias Schmid
Date: 28.09.2026