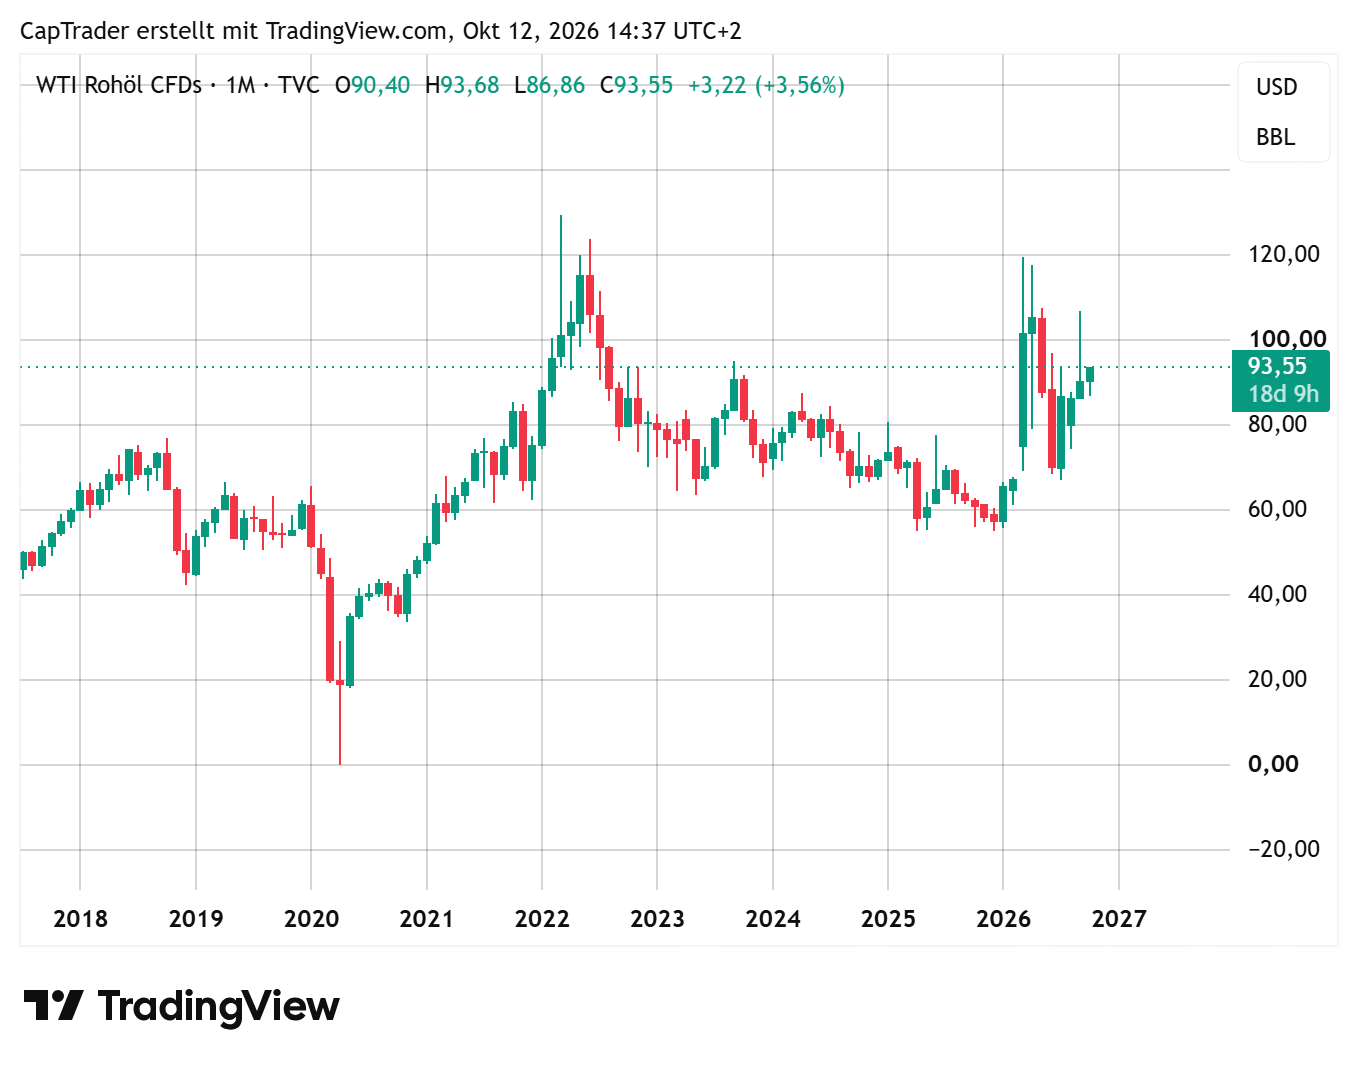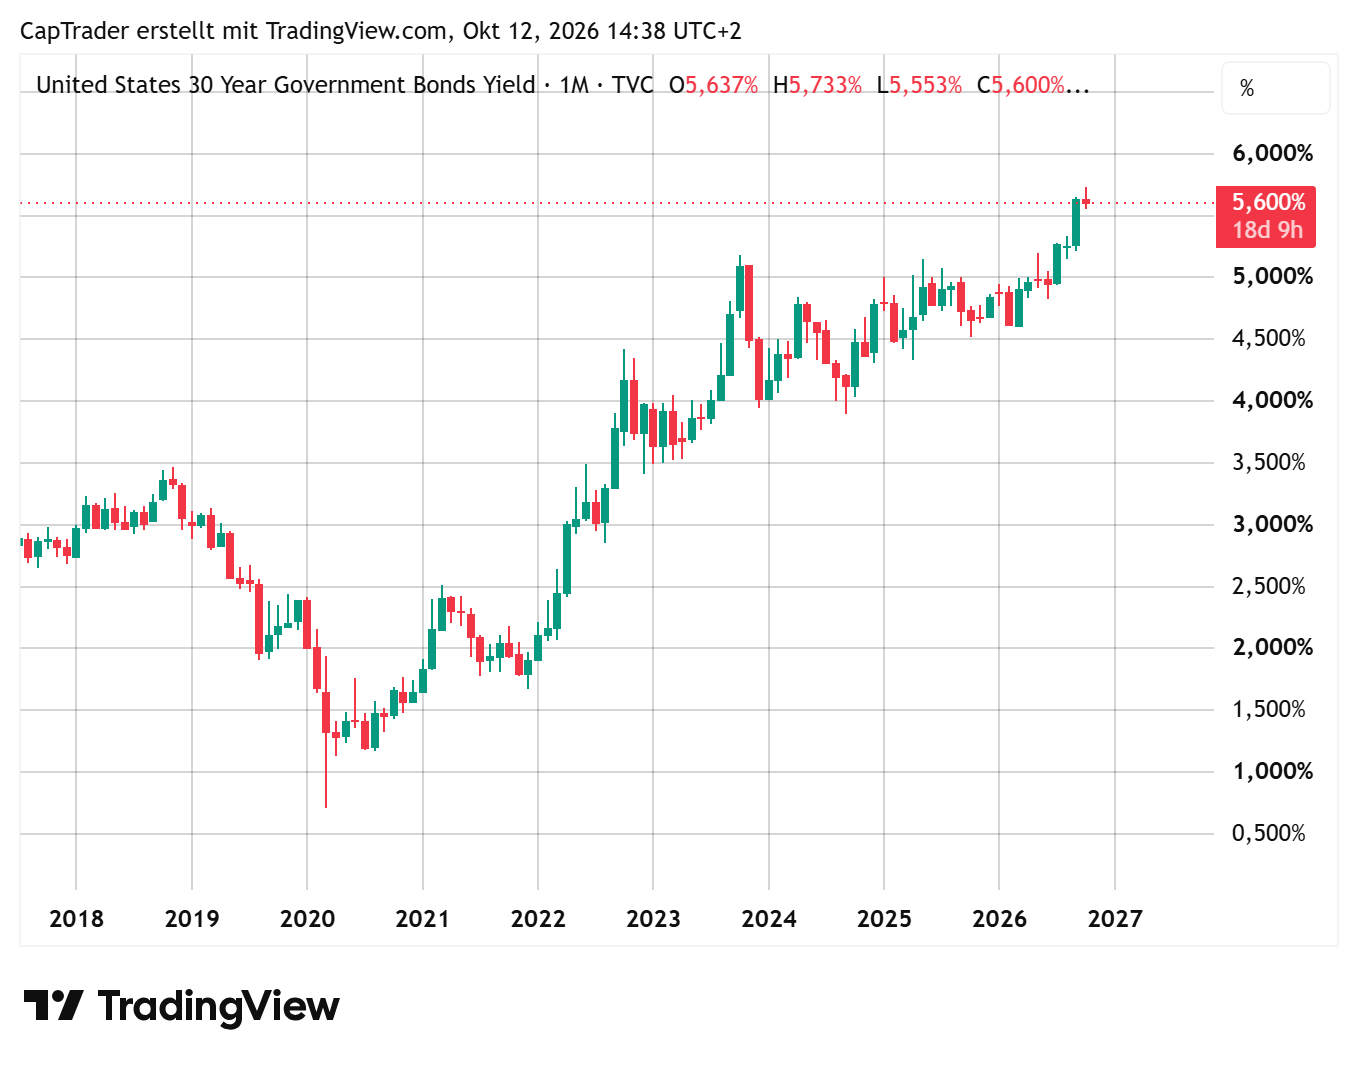
The oil price and bond yields are currently playing a game of ping-pong with investors. Investors continue to balance on the thin line between energy prices and yield expectations. At the same time, the eyes are likely to be focused on the start of the US reporting season. The company results could briefly become a significant driver of the stock markets and mask lingering risk factors, such as Middle East risks. It should be noted that due to "Columbus Day", no trading takes place today in the USA.
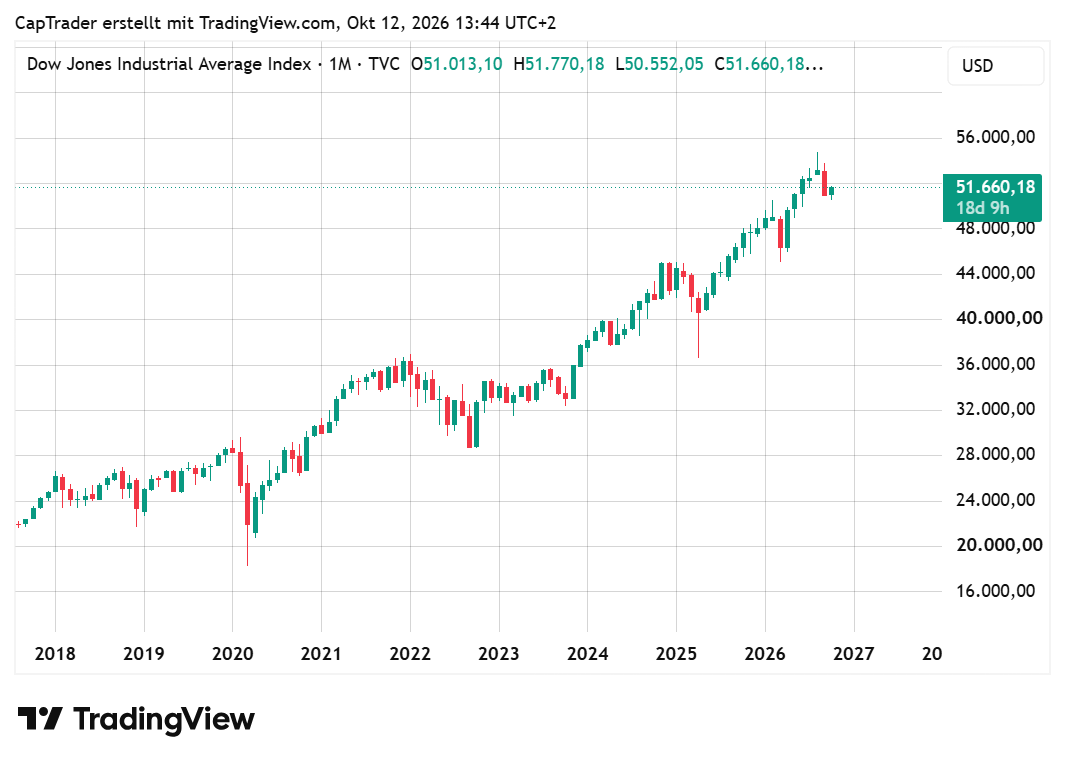
Dow Jones Industrial Average Index
US inflation in focus on Wednesday: Economists expect a rate of inflation of 3.7 percent
This week, investors are focusing in particular on US inflation data (14:30) at the midpoint of the week, which must be taken into account in light of monetary policy signals. Economists expect a month-on-month inflation rate of 3.7 percent for September (compared to August), after 3.4 percent in August. The core inflation rate, which excludes the drivers of energy and food prices, could also rise by 0.1 percentage points to 2.5 percent.
On Thursday, US producer prices and retail sales will be released (14:30).
A speech by Fed Chairman Kevin Warsh is expected to attract attention on Friday (05:30). In this context, monetary policy developments in the US could continue to remain one of the central topics of discussion.
US reporting season in focus starting Tuesday
On Tuesday, Citigroup (ISIN: US1729674242), Goldman Sachs (ISIN: US38141G1040), Johnson & Johnson (ISIN: US47816011046, JP Morgan (ISIN: US46625H1005), UnitedHealth (US91324P1021) and Wells Fargo (ISIN: US9497461015) will present the results of the current financial quarter.
On Wednesday, the figures from Bank of America (ISIN: US0605051046), BlackRock (ISIN: US09290D1019) and Morgan Stanley (ISIN: US6174464486) could cause movement.
Oil price (West Texas Intermediate)