


If you are interested in the Day trading interest, there is no way around the issue of taxes. In Germany Profits from stock market transactions are subject to withholding tax. However, how much, when and where you make these payments depends largely on the structure of your broker! Here you can find out which system is best for you.
Note: Please note that CapTrader does not offer tax advice. We recommend that you always contact a tax advisor who specializes in (international) tax law if you have any questions about taxes.

The most important in a nutshell
- Profits from day trading are subject to withholding tax of 25 percent plus solidarity surcharge
- An allowance of EUR 1,000 per person (EUR 2,000 for married couples and registered civil partnerships) reduces the tax burden
- CapTrader leaves the taxation to you at the end of the year. This allows you to achieve higher profits
Day trading taxes: What private individuals need to consider
More and more people are using the services of modern brokers and taking their finances into their own hands. The Growing interest in day trading In this form of active stock market trading, assets such as shares, currency pairs or derivatives with short maturities are traded.
All positions are closed by the closing bell of the stock exchanges at the latest, thus avoiding the dangerous phase between two trading days. This allows us to control and actively manage our investments when day trading. Leveraged investment products ensure that substantial profits are possible despite the short periods. However, losses can also quickly escalate if handled incorrectly.
However, some traders make handsome profits with the short maturities. Like all Profits from trading on the stock exchange must also be recognized for services rendered by the Day trading taxes be paid. This is where the so-called Settlement tax (formerly also known as "capital gains tax") currently amounting to 25 percent. In addition, the Solidarity surcharge and, if applicable, church tax added.
Fortunately However, solidarity surcharge and church tax are not calculated from the profit, but from the final withholding tax: The 5.5 percent solidarity surcharge and 8 or 9 percent church tax therefore relate to the 25 percent final withholding tax and result in the following values:
| Withholding tax with solidarity surcharge without church tax | 26.3750 percent |
| Withholding tax with solidarity surcharge and church tax 8 percent | 27.8186 percent |
| Withholding tax with solidarity surcharge and church tax 9 percent | 27.9951 percent |
You must pay church tax if you belong to a so-called "public-law religious community". These currently include the Catholic and Old Catholic Churches, the free religious community, several Protestant churches and the Jewish communities. Although many other religious communities meet the requirements for levying such a tax, they currently refrain from doing so. The amount of the Church tax is 8 percent in Bavaria and Baden-Württemberg and 9 percent in the other German states.
Withholding tax and income tax
Currently only day trading tax for private individuals in Germany the final withholding tax including solidarity surcharge tax. The burden is rather high by European standards, but investors benefit from the nature of the tax. not a progressive calculation methodbut a maximum maximum rate.
Also for very high incomes and the application of the top tax rate income from day trading is not taxed differently. This certainly benefits successful traders. There are also opportunities to reduce the tax rate to below 25 percent.
A flat-rate withholding tax, which would be based on income tax and calculated according to tax bracket and tax rate, is always under discussion. In practice, it could lead to even more burdens for day traders, but also offer new opportunities to reduce taxes. It is currently politically unlikely that there will be any short-term changes to the flat-rate withholding tax.
The withholding tax is subject to a personal allowance of 1,000 euros or 2,000 euros for married couples and registered civil partnerships. This is an actual tax-free amount, which means that day trading taxes (or taxes from other profits) only apply to the amount that exceeds EUR 1,000.
There is always confusion about the difference between the tax-free amount and the exemption limit. If an exemption limit is exceeded, the entire amount is taxed. However, if we exceed a tax-free amount, we only pay tax on the excess amount.
How day trading taxes are calculated in Germany
Only on Actual profits from day trading is subject to taxes in Germany. The personal allowance of 1,000 euros, or 2,000 euros for married couples and registered partnerships, is deducted first. If the profit exceeds this amount, the final withholding tax of 25 percent plus solidarity surcharge is deducted from the excess amount.
In practice, this could look like this: You made profits of 10,000 euros from day trading last year and would now like to know how much tax you have to pay on this. To do this, you first deduct your tax-free allowance of 1,000 euros (in our example, you are unmarried). The final withholding tax of 26.3750 percent applies to the remaining EUR 9,000 (in our example, you do not belong to a religious community).
In this case, your day trading tax amounts to EUR 2,373.75 (9,000 x 0.26375). Whether this amount is now due from you as part of your tax return or has already been withheld by your broker depends on the structure of the respective provider.
Summary:
To calculate the day trading tax, only the profit that exceeds the personal allowance. The final withholding tax is then deducted from this sum. If you do not belong to a religious community, which levies a church tax, the charge is 26.3750 percent.
Commercial day trading - What taxes apply?
Who professionally as a day trader is active, the taxed differently than a private individual, who conducts occasional transactions. Depending on the constellation, professional day trading is possible as a freelance activity, as your own company or as an employee.
Taxation for freelancers does not differ from other freelance activities. For example, you can benefit from the basic tax-free allowance of currently 10,908 euros (as of 2023). As long as your earnings from day trading remain below this limit, no tax is levied. The amount can also be topped up, for example with the child allowance of up to 8,952 euros.
Income in excess of your tax-free allowance is subject to your personal income tax rate. The tax burden increases with increasing earnings and can reach the maximum tax rate of 42% if your earnings amount to €61,972 or more per year.
For day trading, for example, use your own Trading-LLC or other, independent company forms, This opens up new opportunities for tax savings. However, your business obligations will also increase. In any case, you should consult a qualified tax advisor to minimize your tax burden.
When does day trading become a trade?
Contrary to rumors to the contrary, the question hangs, whether day trading is carried out privately or commercially, NOT with the amounts traded or the quantity of trades together. The assertion that professional day trading exists if no other activity is carried out is also incorrect.
In practice there are There are only very few cases in which day trading is classified as an entrepreneurial activity. This includes, above all, the group of people for whom trading takes place and the origin of the capital: A day trader who trades exclusively with his own assets (no third-party assets!) on his own account does not meet the definition of a commercial trader. This also applies when large sums are moved in hundreds of trades per day. Court rulings confirm this view time and again.
If, on the other hand, day trading is (also) carried out for others or with third-party assets, this generally constitutes an entrepreneurial activity. This also applies if you pass on your financial knowledge, day trading know-how etc. to third parties as a teacher in return for payment!
Good to know:
Anyone who passes on their financial knowledge in paid seminars or coaching sessions is acting commercially and must take care of the corresponding registrations and taxation.
The classification is ultimately always the responsibility of the tax authorities and has already led to many a lengthy legal dispute. If you do not agree with the tax office's approach, legal assistance may be useful in certain circumstances.
Domestic or foreign brokers? What you should bear in mind
Thanks to the Internet, it is now easier than ever, to select the right broker. You are no longer dependent on providers in your area, such as the often expensive house bank. Also Service providers from other EU countries or international countries are eligible for German investors.
When, where and how much day trading tax is levied depends on your location and that of your broker. There are generally two options:
- The broker is based in Germany. In this case, the Withholding tax of 25 percent of any profits you make with such a provider, retained directly. You can generally claim your exemption amount if you issue a corresponding exemption order to your German broker. This means that only profits that exceed the 1,000 euro mark are subject to the 25 percent withholding tax.
- The broker is not based in Germany and does not automatically deduct the final withholding tax for you. You are obliged to declare your winnings correctly in your next tax return. If your income exceeds your exemption limit of EUR 1,000, your tax office will charge 25% flat-rate withholding tax on this amount.
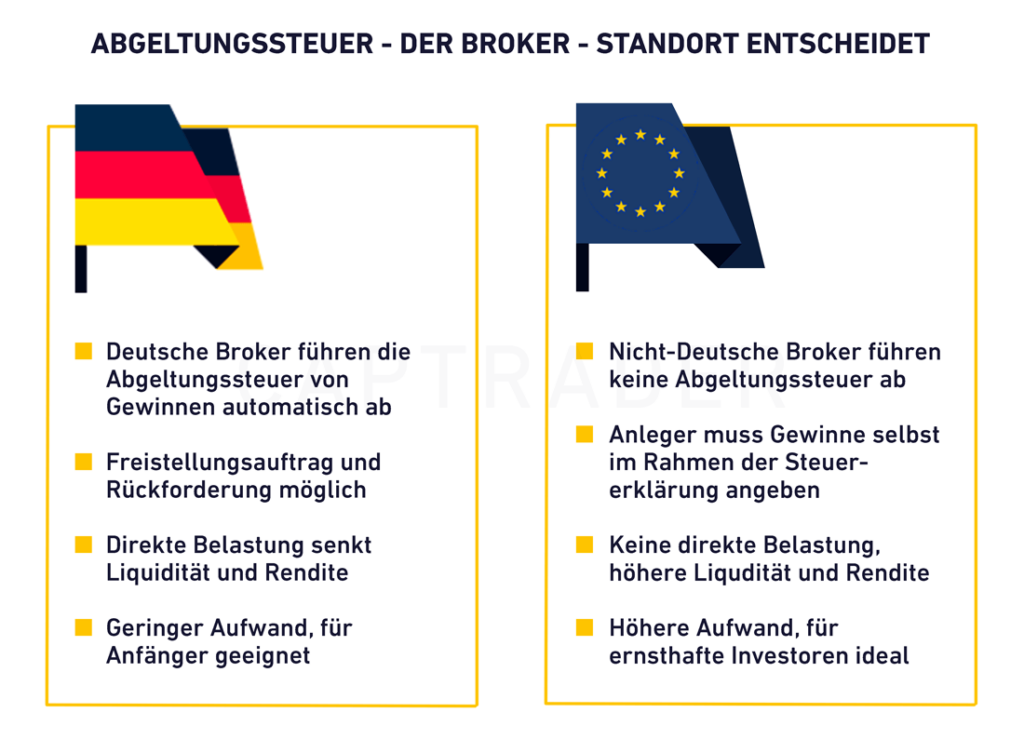
The two variants have own advantages and disadvantages. If you are interested in a German broker you benefit from a particularly simple way of paying your withholding tax. Thanks to automatic payment, you do not have to actively take care of your day trading taxes yourself. Unfortunately, this also results in a significantly greater load.
As the withholding tax is always deducted directly from your profits, you cannot initially offset this against your losses. As even the best day trader occasionally makes mistakes, this disadvantage will be noticeable in the long term. Only at the end of the year you can use the KAP appendix in your tax return to report the taxable income you reclaim any excess withholding tax paid.
You are missing the sum However, you could have generated further profits in the past few weeks or months. As a result, the direct deduction of withholding tax reduces your liquidity and reduces your return. Pay the day trading taxes in this way, is therefore simpler, but not lucrative and is particularly suitable for non-experts who want to take their first steps on the financial markets.
If, on the other hand, you opt for a non-German brokers, This problem is eliminated: the provider will not automatically deduct the final withholding tax for you, so that you can keep your Declare profits in your tax return must. The allows you to continue day trading with the full amount, as you have not yet had to pay any tax and the profits are still available in your account. In practice, paying the final withholding tax can be postponed by up to 1.5 years become!
Personal taxation does, however, mean slightly more work when submitting your tax return. Non-German brokers are therefore ideal for all day traders who want to keep their tax burden low and optimize profits.
With CapTrader you will receive such an offer, which The convenience of a German company with the liquidity advantage of a non-German broker links: due to our structure, we are not considered a German broker and therefore do not automatically deduct withholding tax for you. You therefore enjoy a considerable financial advantage. At the same time, however, we are a company based in Germany with German customer service and all the other amenities you would expect from a regional service provider.
Offsetting profits and losses
The higher your profits from day trading, the higher the amount you have to pay in tax. However, of this income the losses incurred are deducted. Since individual trades may not work out as desired in short-term trading, this process is particularly important for day traders.
This deduction is more difficult for brokers based in Germany and can only take place retrospectively, through the tax return. This is because the final withholding tax has already been withheld by the provider in this case, but has not yet been offset against the losses. The amount can be reclaimed via the KAP annex, but is not available until the payout, which lead to considerable liquidity losses can.
Brokers outside Germany do not deduct withholding tax from your profits so that you can offset them against losses in your tax return. Until then your capital remains available and can generate further returns.
Regardless of whether you opt for a German or foreign broker, the following applies offsetting losses is an important process to reduce your tax burden. As some investors make losses when day trading, the idea of offsetting these against profits from other asset classes is an obvious one. However, this is not possible in practice, as the "horizontal loss compensation" grabs!
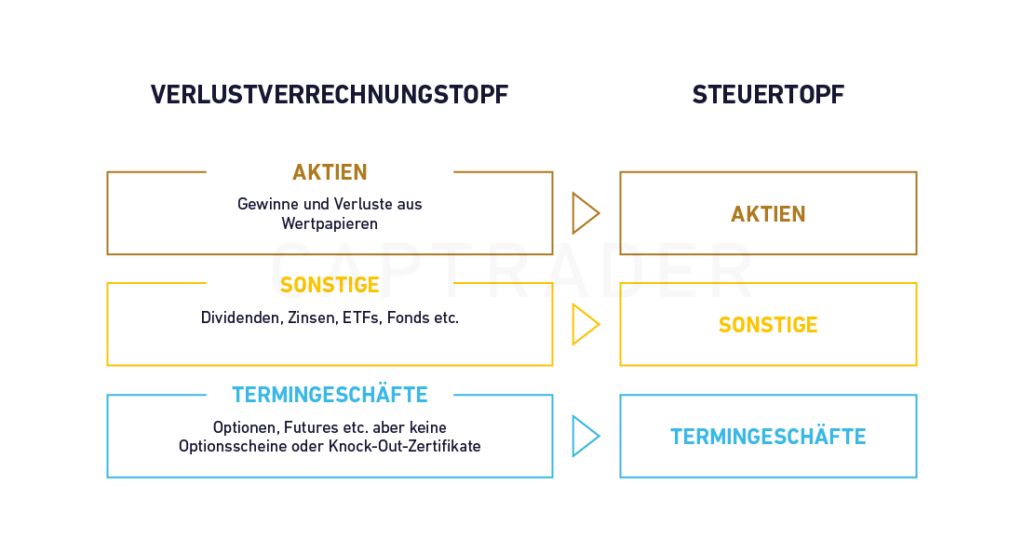
This means that losses can only be incurred within the same type of income, the respective "settlement pot", be offset. If you have lost money through day trading with futures, you cannot deduct these losses from your interest income or your dividends!
If your losses have exceeded last year's profits but you cannot reduce your tax burden any further, a so-called "Loss carryforward" useful. With this take your losses into the next year, so that you benefit from the tax reduction there.
Good to know:
Transaction costs, expenses and other fees that your broker may charge are also deducted from your profits, thus reducing your tax burden.
Save taxes on day trading: Here's how
With the exception of the few professional retailers for almost all Day trading profits the final withholding tax of 25 percent, which increases further due to the solidarity surcharge.
In some cases, however, the burden can be reduced. This is possible, for example, if the day trader has a lower income tax rate than the 25 percent withholding tax. As part of a so-called "More favorable review" the person concerned can request an investigation into the possible assessment and subsequent use of the lower tax rate.
There are also other options, such as something the establishment of a trading GmbH. Such companies are set up with the aim of making profits on the financial markets and enjoy preferential tax treatment. If you want to save on day trading taxes, the help of a tax advisor is always advisable!
Day trading with different assets - these taxes apply in Germany
With the Withholding tax, the burden for different asset classes was such as shares, derivatives, interest income and other standardized. The previously different calculation methods and tax rates were merged into a uniform rate of 25 percent plus solidarity surcharge.
In practice, this results in the following tax burden for day trading:
1. shares
For day trading with shares, the Withholding tax of 25 percent plus solidarity surcharge and, if applicable, church tax. The regulation according to which share gains were tax-free if the securities were held for at least one year has no longer applied since 2009.
2. forex/foreign exchange
Day trading with currency pairs can be viewed in two different ways for tax purposes: If there is a delivery claim against the broker If a day trade takes place before the end of the day, it is a purchase/sale of a real asset. The day trader must In this case, declare net income in your tax returnwhere they then with the personal income tax rate be offset.
If such an extradition claim does not exist and the contract with the broker provides for a cash settlement instead, the withholding tax applies. This is because in this case - from the point of view of the authorities - no real goods are traded and the day trader is not the owner of the respective currency.
3. forward transactions (options, futures, ...)
Also for forward transactions the final withholding tax generally applies. Profits are taxed at 25 percent plus solidarity surcharge, losses can be offset. However, such deductions must remain in the area of futures transactions, i.e. if you have made losses with futures, you cannot offset them against your interest income, for example. From a tax perspective, warrants and knock-out certificates do not count as futures transactions. Instead, we can offset losses made here against "other securities".
Conclusion: Taxes play an important role in day trading
The topics Day trading and taxes are inextricably linked. Even those who are only active occasionally and trade on individual days will come into contact with the flat-rate withholding tax. As the majority of users make losses when day trading, it is particularly important to be aware of this. offsetting with profits from the same type of offsetting is of great importance. For example, losses in the Day trading with shares against gains from shares, losses from currency transactions against gains from currency transactions, etc.
In general, with a few exceptions, the final withholding tax always applies to profits from day trading. This amounts to 25 percent plus the solidarity surcharge, which corresponds to 5.5 percent of the final withholding tax. For members of some religious communities, there is also a church tax of 8% (Bavaria and Baden-Württemberg) or 9% (other federal states), which is also calculated from the tax.
This general taxation can only be influenced to a limited extent. Anyone who has a lower tax rate can have this invested instead of the flat-rate withholding tax. We also benefit from the tax-free allowance of currently 1,000 euros per person for profits.
The importance of the broker is often underestimated! A foreign institute, such as CapTrader, leaves the calculation of the withholding tax to you. This gives you a considerable liquidity advantageThe money is available to you until it is transferred to the tax office and can generate considerable returns. This period, which can easily be one and a half years, does not apply to German brokers, as they deduct your tax immediately.
Choosing the right broker can make a massive financial difference, as the 25 percent of your profits are available to you for longer. Apart from this, day traders unfortunately have few options to reduce their taxes.
