Opens in a new tab
Your Broker for worldwide trading

S&P 500 Analysis: Weak Market Breadth Meets Seasonal Buying Opportunity

Dear traders, dear stock market friends.

In recent weeks, the performance of the S&P 500 appeared to be heavily driven by daily news. The Middle East conflict, fluctuating oil prices, rising bond yields, inflation data, the U.S. labor market, and the Federal Reserve's future monetary policy repeatedly caused short-term price movements.

Especially in such market phases, however, it is particularly important to tune out the daily news noise and instead analyze as calmly as possible where capital is actually flowing. After all, all of this information, expectations, and positioning are ultimately reflected in prices. Looking at the charts and, in particular, at market breadth therefore frequently provides more valuable insights than attempting to interpret every single piece of news and every short-term market reaction.

S&P 500 defends weekly EMA 20

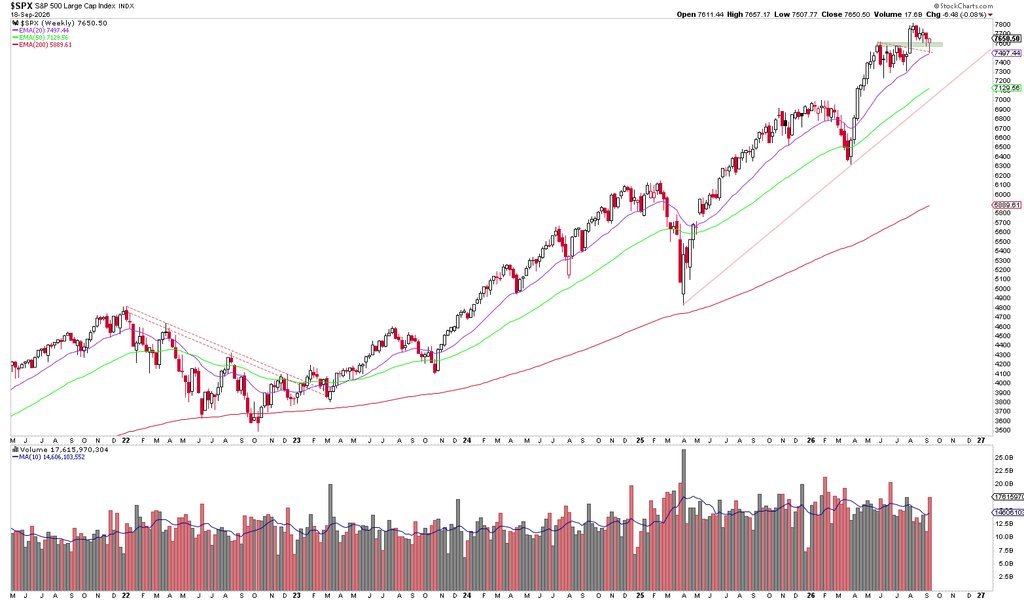
Taking a look at the long-term trend on the weekly chart, the technical picture of the S&P 500 initially looks completely healthy. Following the breakout to the all-time high in the trading week starting August 3, the index corrected back to the breakout level (the former all-time high) and formed a reversal signal there last week in the form of a hammer candlestick pattern. The correction extended only as far as the 20-week EMA (purple). This shows that strong bullish momentum is still present.
S&P 500 weekly chart

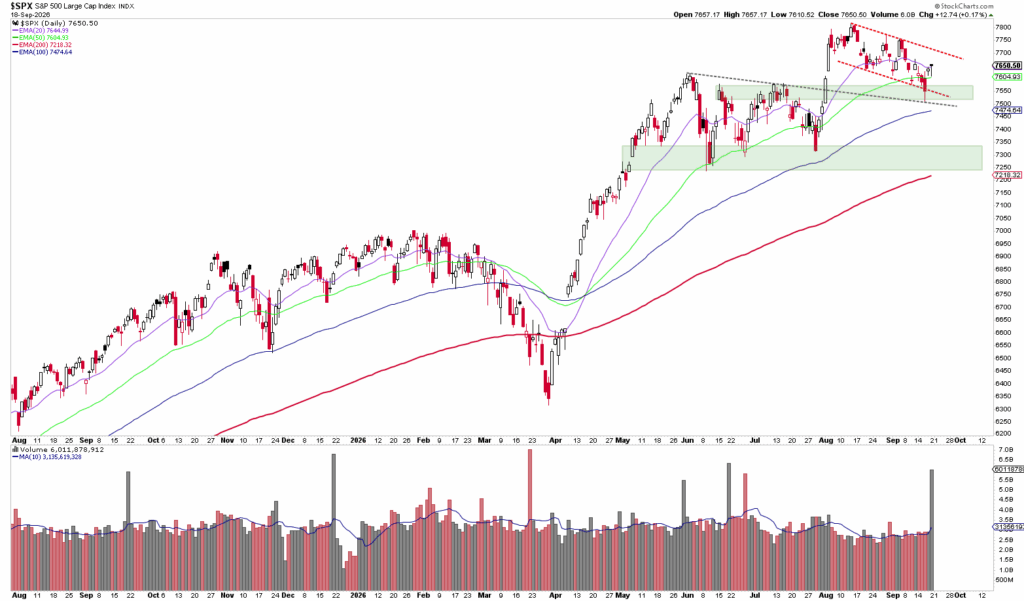
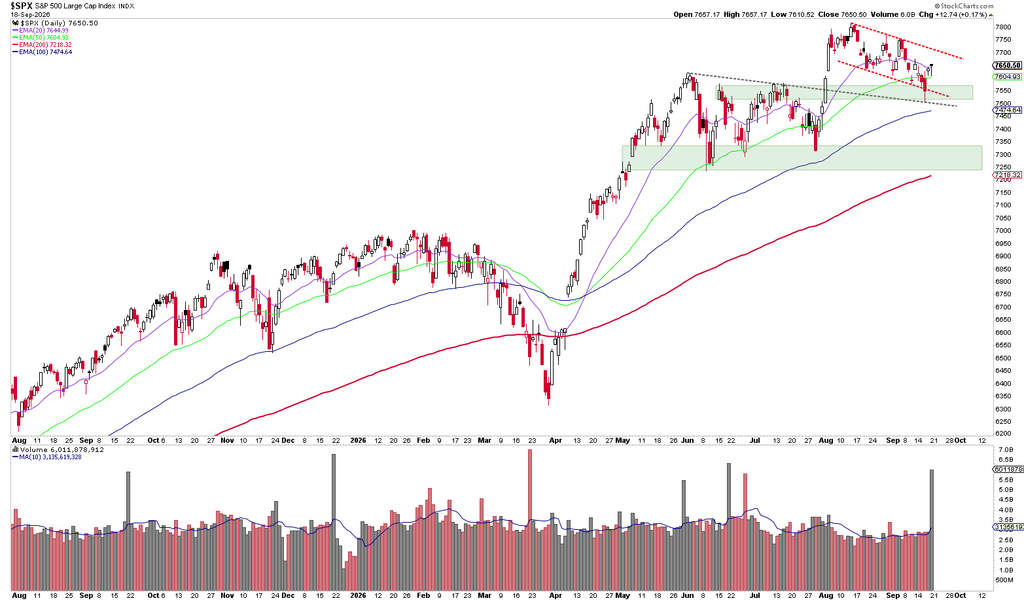
The daily chart also shows that the currently relevant short-term support is in the area of around 7,500 points. In addition to the weekly EMA 20, the old broken downtrend line runs here and a few points below that is the daily EMA 100. In addition, the local highs from June and July provide horizontal support.

Should this support zone not hold, the next correction target would be around 7,250 - 7,300 points.
S&P 500 daily chart

Market breadth shows clear weakness signals

In addition to looking at the index itself, market breadth analysis often provides very reliable signals, which are considered leading indicators in particular. Bullish signals in the S&P 500 must be confirmed by market breadth for a trend to be considered “healthy.” A divergence between the index and market breadth, on the other hand, is an important warning signal.

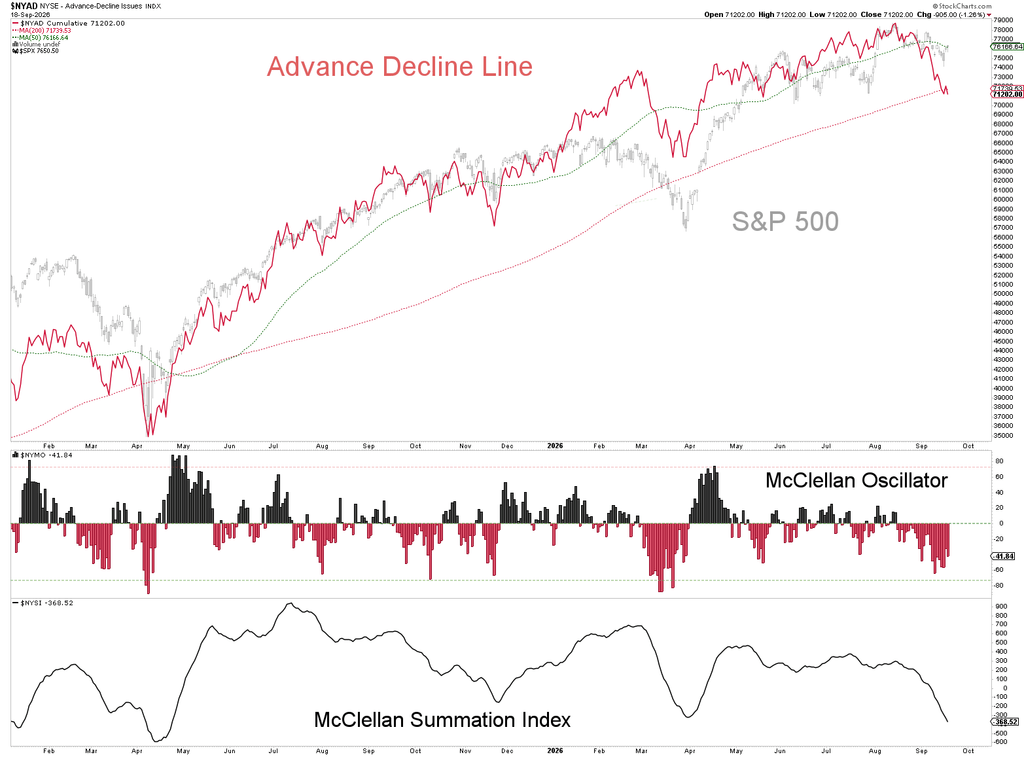
Precisely such a divergence currently exists. While the S&P 500 Index is in a completely intact upward trend and is trading only two percent below its all-time high, market breadth is already showing signs of weakness.

The Advance-Decline line has been in a steep downward trend since mid-August, and the McClellan Oscillator (which is based on the Advance-Decline Line) is also signaling bearish market breadth momentum.
Advance Decline Line Tageschart

Despite the recent downward movement of the AD Line, the long-term upward trend is not yet broken. A stock market correction is usually also accompanied by weakness in market breadth, which is why current developments represent an important warning sign, but should not (yet) be seen as a harbinger of a trend reversal in the S&P 500. This would only be the case if the divergence between the S&P 500 and the AD Line continues and a clear downward trend emerges in the AD Line.

The number of new 52-week highs and 52-week lows on the New York Stock Exchange (NYSE) also confirms the trend of the advance-decline line. Throughout September, there were more stocks with new 52-week lows than stocks with new 52-week highs on every single day.
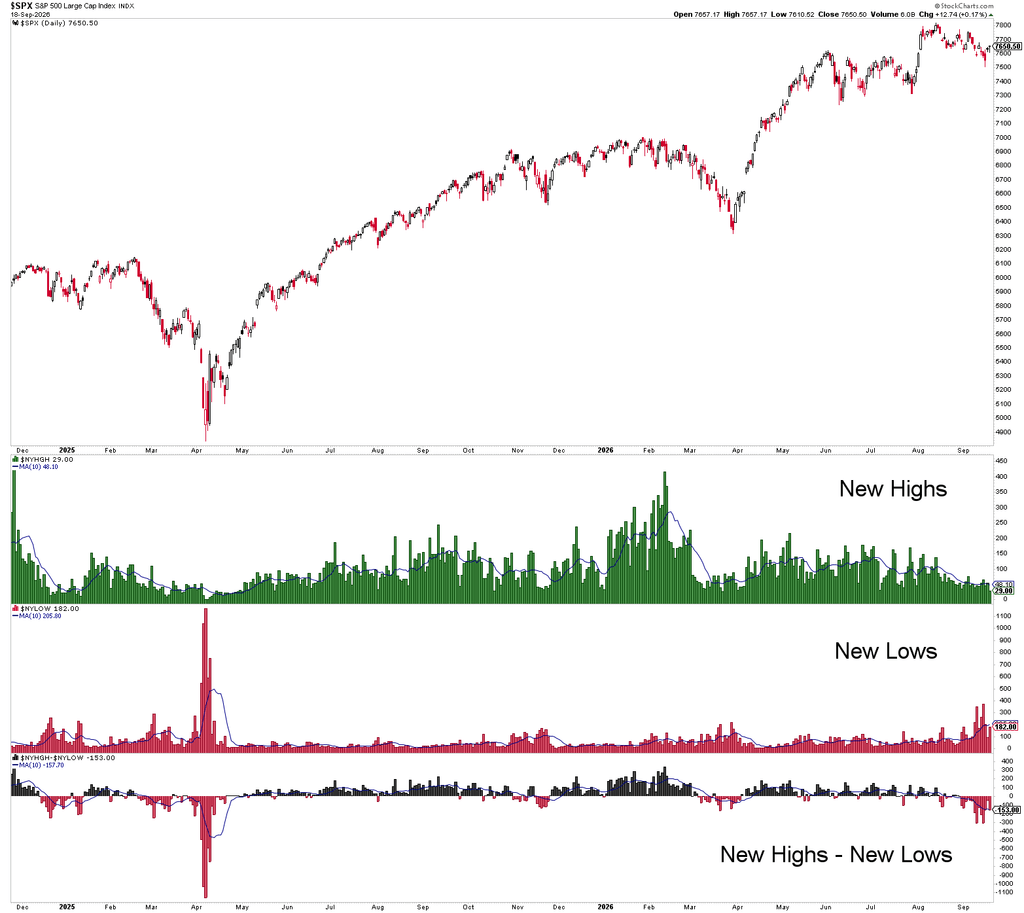
NYSE New Highs vs New Lows

Moreover, only 52 % of all stocks in the S&P 500 are currently above their 200-day simple moving average. The 200-day line is considered an indicator of the long-term trend. When 50 % of all stocks or fewer follow the index's trend, this is usually a clear sign that increasing weakness and declining market breadth are already becoming apparent beneath the surface. While the index may continue to hold at a high level, it is then supported by fewer and fewer stocks. At the New York Stock Exchange, this figure has already fallen below the 50 percent threshold and stands at 45 %.
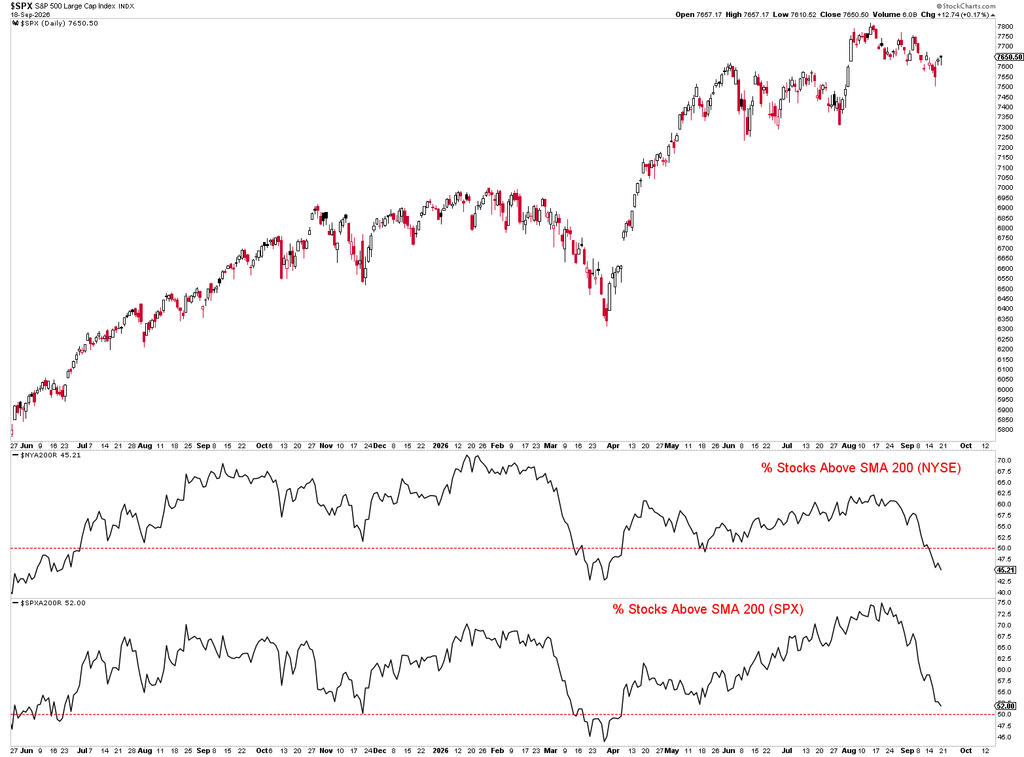
% Stocks above SMA 200 (S&P 500 & NYSE)

S&P 500 is (still) in the seasonally weakest phase of the year

However, when classifying this weakness, seasonality must not be disregarded. Historically, September is one of the weakest months of the year for the US stock market. A correction of the S&P 500 is therefore by no means unusual during this phase. At the same time, this seasonal weakness is frequently accompanied by a deterioration in market breadth.
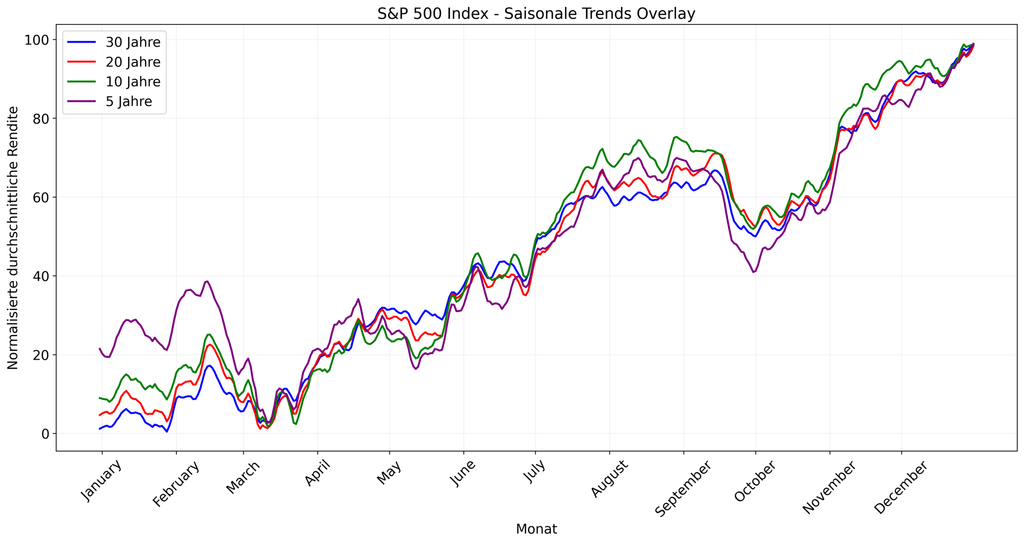
S&P 500 - Seasonal Trends

Therefore, it will be crucial how the market behaves in the coming weeks. The bullish case would remain completely intact if the S&P 500 starts a new upward movement towards the end of September or in October and this rally is once again supported by a broader number of stocks. A recovery of the Advance Decline Line as well as an increasing percentage of stocks above their important moving averages would be important confirmation signals in this regard.

NYSE Composite Index oversold

With the correction of the past few weeks, we saw another interesting development: the number of stocks on the New York Stock Exchange trading above the 20-day SMA is currently only 21.7 %. The 20 percent mark is usually a threshold signaling that the market is oversold. In an intact bull market, this signal often presents good buying opportunities. As can be seen in the chart below with the green dashed horizontal lines, precisely these points in time in the past have mostly led to a new upward movement.
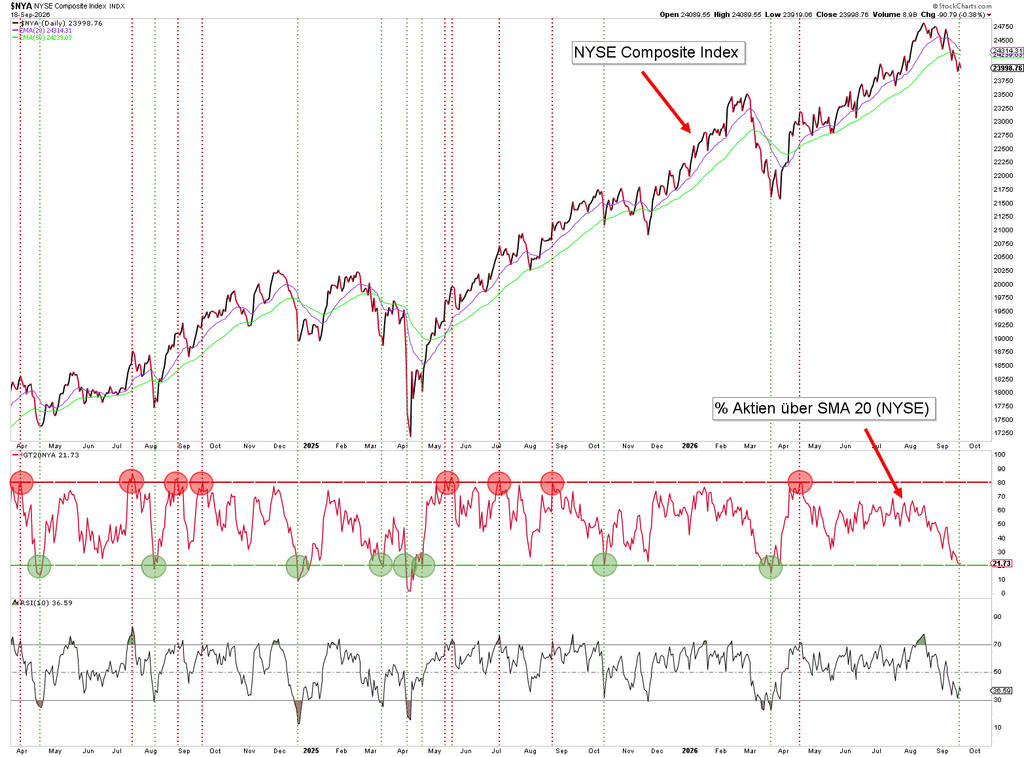
NYSE Composite Index & Percent of Stocks above SMA 20

Conclusion: Bull case remains intact (for now)

The long-term upward trend of the S&P 500 remains intact. At the same time, the seasonally weakest phase of the year is coming to an end. Historically, a significantly more favorable stock market phase follows, which is why late September and October often present attractive entry opportunities within an ongoing bull market.

The currently heavily oversold signal in the percentage of NYSE stocks above their 20-day SMA also suggests that a new upward movement could be imminent. Especially within an intact bull market, comparable signals have worked very reliably in the past.

The development of the coming weeks will be all the more interesting. If no sustained recovery begins despite the oversold condition (NYSE % Stocks above SMA 20), the approaching seasonally stronger phase, and the still intact long-term upward trend, this would be a clear warning sign. In that case, the current weakness in market breadth would also have to be evaluated much more critically.

Author: Tobias Schmid
Date: 09/21/2026
A man with slicked-back hair and a trimmed beard, wearing a navy blue suit jacket and a white shirt, looks into the camera with a slight smile. Industrial background.
Tobias Schmid

Tobias Schmid has been a trader and analyst since 2008 and specializes in trading futures options and equity options. His strategies and analysis methods are based on a combination of technical analysis, intermarket analysis and sentiment analysis. Tobias Schmid is also the founder of Fomo Financea financial website for active traders, investors and options traders.

Mandatory information and disclaimer

This is a marketing communication within the meaning of Section 63 (6) of the German Securities Trading Act and does not contain investment strategy recommendations, investment recommendations or financial analyses in accordance with Section 85 of the German Securities Trading Act and Article 20 of the Market Abuse Regulation. It therefore does not fulfill the legal requirements to guarantee the objectivity of investment strategy recommendations/investment recommendations/financial analyses. CapTrader GmbH or its employees are therefore not legally prohibited from trading or providing services in the securities products mentioned therein prior to publication of the information.

Past performance, simulations or forecasts are not a reliable indicator of future performance. Mandatory information and limitation of liability for CapTrader and any third-party content providers can be found at https://www.captrader.com/marketingmitteilung/angaben
Please note that investing in financial instruments involves high risks and take note of our disclaimer and the mandatory legal information at the locations indicated.

  1. Mandatory information

Responsible: CapTrader GmbH, Elberfelder Straße 2, 40213 Düsseldorf; Commercial Register Number: HRB 86537 Düsseldorf Local Court; VAT ID DE323771603; Managing Directors Andreas Weiß, Christian Weiß, Michael Heyder; Tel: +49 211-740786-00, Fax: +49 211-740786-90.

Zuständige Aufsichtsbehörde: Bundesanstalt für Finanzdienstleistungsaufsicht, Graurheindorfer Straße 108, D – 53117 Bonn und Marie-Curie-Str. 24-28 D – 60439 Frankfurt am Main, Tel: 0228 4108 – 0 Fax: 0228 4108 1550 E-Mail: poststelle@bafin.de; Institutsnummer 10156708

Conflicts of interest CapTrader in marketing communications: CapTrader GmbH confirms that it does not hold any positions in the mentioned financial instruments beyond the positions mentioned in the marketing communication itself, if applicable. There are also no other conflicts of interest within the meaning of CapTrader GmbH's Financial Analysis and Marketing Communication Policy.

Conflicts of interest and mandatory disclosures by the third-party content provider for marketing communications with financial instrument recommendations: See under https://www.captrader.com/marketingmitteilung/angaben  to creators of third-party content

The copyright to the marketing communication is reserved. Reprinting and distribution is only permitted with our consent.

  1. Disclaimer

By accepting the content, the recipient accepts the binding nature of the limitation of liability.

a) Disclaimer for third-party content

CapTrader GmbH offers authors - such as editors, guest commentators, agencies and companies - the opportunity to publish comments, analyses, news and company announcements. Their opinions do not necessarily reflect the opinions and views of CapTrader GmbH and its employees. CapTrader GmbH assumes neither liability nor guarantee for this content. This applies in particular to incomplete or incorrectly reproduced reports, incorrect price information and editorial errors. Liability claims relating to material or immaterial damage caused by the use or non-use of the published information or by the use of incorrect or incomplete information are fundamentally excluded.

b) Exclusion of liability for CapTrader's own content

CapTrader has taken its own information in this marketing communication from sources believed to be reliable, but has not verified all such information itself. Accordingly, CapTrader makes no warranties or representations as to the accuracy, completeness or correctness of the information or opinions contained herein. Subsequent changes cannot be taken into account. The marketing communication does not constitute an offer or solicitation to buy shares of the issuer and is in no way a substitute for advice appropriate to the investor and the property. We cannot verify whether the information in the marketing communication is in line with your personal investment strategies and objectives. We recommend that you consult an investment advisor for advice that is appropriate to the investor and the property. The marketing communication cannot and should not replace a securities prospectus and/or expert investment advice required for an investment. It can therefore never be the sole basis for an investment decision. By accepting the marketing communication, the recipient accepts the binding nature of the above limitation of liability.

CapTrader provides the information despite careful procurement and provision only without guarantee for the correctness / completeness, timeliness or accuracy and availability of the stock exchange and economic information, prices, rates, indices, general market data, valuations, assessments and other accessible content held and displayed for retrieval. This also applies to third-party content. Historical observations and forecasts are not a reliable indicator of future developments. The facts presented in particular in connection with product information are for illustrative purposes only and do not permit any statements to be made about future profits or losses. Any conditions stated are to be understood as non-binding indications and are dependent on market developments on the day of conclusion.

CapTrader accepts no liability for any direct or indirect damage caused by and/or related to the distribution and/or use of this marketing communication.

The information, opinions and statements correspond to the status at the time of preparation of the marketing communication. They may be outdated due to future developments without the publication being changed.

CapTrader is not obliged to update, amend or supplement the information in this marketing communication if a circumstance mentioned in this publication or a statement, estimate or forecast contained therein changes or becomes inaccurate. The presentation of the performance of financial instruments over previous periods does not provide a reliable indication of their future performance. No guarantee can therefore be given for the future price, value or income of any financial instrument mentioned in this publication.

Despite careful control of the content, we assume no liability for the content of external links. The operators of the linked pages are solely responsible for their content.

Distribution: This publication may only be distributed in accordance with the laws of the respective countries, and persons in possession of this publication should inform themselves about the applicable local regulations. The information contained herein is not intended for natural or legal persons who, due to their place of residence or business, are subject to a foreign legal system that imposes restrictions on the distribution of such information. The contents are therefore exclusively in German. In particular, this publication contains neither an offer nor an invitation to purchase securities to citizens of the USA, Great Britain and Australia.

Taxes: The tax treatment of financial instruments depends on the personal circumstances of the respective investor and may be subject to future changes, which may also have a retroactive effect.

Historical observations and forecasts are not a reliable indicator of future developments. The facts presented in particular in connection with product information are for illustrative purposes only and do not permit any statements to be made about future profits or losses. Any conditions stated are to be understood as non-binding indications and are dependent on market developments on the day of conclusion.

CapTrader accepts no liability for direct or indirect damage caused by and/or in connection with the distribution and/or use.

The information, opinions and statements correspond to the status at the time of preparation of the marketing communication. They may be outdated due to future developments without the publication being changed.

CapTrader is not obliged to update, amend or supplement the information if a circumstance mentioned in this publication or a statement, estimate or forecast contained therein changes or becomes inaccurate. The presentation of the performance of financial instruments over previous periods does not provide a reliable indication of their future performance. No guarantee can therefore be given for the future price, value or income of any financial instrument mentioned in this publication.

Despite careful control of the content, we assume no liability for the content of external links. The operators of the linked pages are solely responsible for their content.

Distribution: This publication may only be distributed in accordance with the laws of the respective countries, and persons in possession of this publication should inform themselves about the applicable local regulations. The information contained herein is not intended for natural or legal persons who, due to their place of residence or business, are subject to a foreign legal system that imposes restrictions on the distribution of such information. The contents are therefore exclusively in German. In particular, this publication contains neither an offer nor an invitation to purchase securities to citizens of the USA, Great Britain and Australia.

Taxes: The tax treatment of financial instruments depends on the personal circumstances of the respective investor and may be subject to future changes, which may also have a retroactive effect.

Email:

info@captrader.com

Send e-mail

Phone:

Hotline (Germany)
0800-8723370

Hotline (International)
00800-08723370

Further contact options