Opens in a new tab
Your Broker for worldwide trading

S&P 500 to rise further in 2026 if...

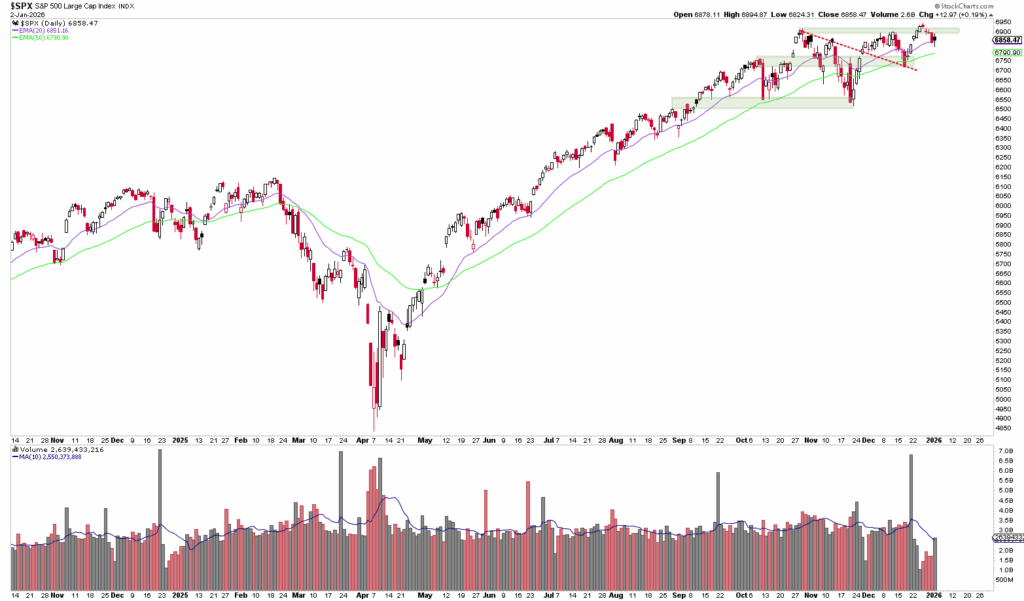
Line chart of S&P 500 price performance from January 2020 to January 2021 with trading volume bars and 20- and 50-day moving averages, highlighting the rise as a possible indicator of trends through 2026.

Dear traders, dear stock market friends.

In the past trading week, the S&P 500 was still in vacation mode and trading volumes were extremely low. After the index reached another all-time high on Christmas Eve and successfully ended the year 2025, a moderate correction of around one percent followed last week. The focus is now turning to the new year and the question of whether the S&P 500 can go one better despite its already high valuation and strong performance in recent years, or whether the risk of a major correction has increased.

S&P 500 posts double-digit gains for the third year in a row

With a closing price of 6845.50 points, the S&P 500 ended 2025 with a gain of 964 points or +16.4 %. All in all, 2025 was a strong year for equities, and clearly above the long-term average: historically, the average annual return of the S&P 500 (since 1957) is around 10.6% p.a. At +16.4%, the market has clearly exceeded this „normal value“.

At the same time, 2025 was not an exceptional year like 2023 or 2024, but rather a kind of normalization at a high level: After price increases of more than 20 % in the previous years 2023 and 2024, the increase in 2025 was lower, but remained comfortably in double digits. (If dividends are included, the total return for 2025 is even just under +17.9%).

Nevertheless, there were a few records: 

  • The S&P 500 reached 39 new record highs in 2025. (However, this number is not unusually high).
  • And symbolically important: On December 24, 2025, the index reached its all-time high at a closing price of 6,932.05 points, followed by an intraday all-time high of 6,945.77 points on December 26.
  • Although this fell just short of the magic 7,000 mark, the market visibly "docked at the top" at the turn of the year.
  • To put this into perspective: It is historically rather rare for the S&P 500 to post double-digit gains for three years in a row (2023-2025). It is only the sixth time since the 1940s that this feat has been achieved. And this also explains the big macro question that directly resonates in 2026: Can the market continue the streak, despite already high valuations and a strong AI/mega-cap weight?

All 11 market sectors of the S&P 500 up

The S&P 500 can be divided into 11 market sectors. An ETF is available for each of these sectors, which can be used for both investment and analysis. Below we compare the performance of the individual market sectors with the S&P 500 ETF (SPY) over the last 52 trading weeks, more precisely from January 02, 2025 to January 02, 2026: 

  • The SPY rose 18.23 %.
  • All 11 market sectors are up.
  • The Technology (+25.19%), Industrials (+21.97%) and Communication Services (+21.63%) sectors were particularly strong. These three market sectors are offensive or pro-cyclical sectors. Only Consumer Discretionary, another important offensive sector, was weaker than the index.
  • The three most important defensive sectors (Consumer Staples, Health Care and Utilities) were also strong, but underperformed the index and in particular the offensive market sectors.
Bar chart of S&P 500 sector performance from January 12-26, 2023; Technology led with +7.01%, while Utilities and Real Estate underperformed in this auto-saved draft.
SPY and the eleven sector ETFs of the S&P 500 (absolute performance, Jan. 2, 2024 - Jan. 2, 2025)

The bottom line is that the offensive market sectors led the way last year and the defensive sectors showed relative weakness. The relative performance of the individual sectors compared to the SPY becomes particularly clear when we visualize the outperformance/underperformance on a relative level with a performance chart.

Bar chart of S&P 500 sector performance for January 2023. Top gainers: Consumer Discretionary, Communication Services, Technology. Losing sectors: Energy, Health Care, Utilities, Real Estate. Automatically saved draft included.
Relative performance of the eleven sector ETFs of the S&P 500 (Jan. 2, 2024 - Jan. 2, 2025)

This is exactly the kind of development we want to see in a healthy bull market (outperformance of offensive sectors, underperformance of defensive sectors). As long as nothing changes in this picture and the pro-cyclical sectors continue to lead the way, the long-term uptrend should not be in danger.

Profit growth at record level

Social networks are currently full of posts pointing out the high valuation of the stock market and the S&P 500 and warning of a stronger correction as a result. 

While a correction of +/- 10 % is certainly possible at any time and is historically the rule rather than the exception, one must not forget that the high valuation is not just pure hype based on fantasy, but is supported by real earnings growth.

It is also worth taking a sober look at the valuation figures: Depending on the definition, the current P/E ratio of the S&P 500 (trailing, last 12 months) is around 31, which seems high at first glance. However, if you look at the forward P/E ratio (earnings over the next 12 months), which is often more important in practice, the market currently stands at around 22, which is also above the historical average range: FactSet puts the 10-year average forward P/E roughly at 18.6 (5-year average around 19.9). 

However, it is crucial that this valuation is not viewed in isolation, but in relation to the companies' earnings growth: For 2025, the expected earnings growth of the S&P 500 is around +12% according to the FactSet consensus, and for 2026, the current forecast is even around +15%; both clearly above the long-term earnings growth average. 

This is precisely why the market can remain stable despite ambitious multiples: as long as companies deliver (and there are no surprising headwinds from inflation/interest rates), an expensive market is not automatically an overheated market. The risk only arises when expectations become too high and reality no longer catches up with them.

Author: Tobias Schmid
Date: 05.01.2026
A man with slicked-back hair and a trimmed beard, wearing a navy blue suit jacket and a white shirt, looks into the camera with a slight smile. Industrial background.
Tobias Schmid

Tobias Schmid has been a trader and analyst since 2008 and specializes in trading futures options and equity options. His strategies and analysis methods are based on a combination of technical analysis, intermarket analysis and sentiment analysis. Tobias Schmid is also the founder of Fomo Financea financial website for active traders, investors and options traders.

Mandatory information and disclaimer

This is a marketing communication within the meaning of Section 63 (6) of the German Securities Trading Act and does not contain investment strategy recommendations, investment recommendations or financial analyses in accordance with Section 85 of the German Securities Trading Act and Article 20 of the Market Abuse Regulation. It therefore does not fulfill the legal requirements to guarantee the objectivity of investment strategy recommendations/investment recommendations/financial analyses. CapTrader GmbH or its employees are therefore not legally prohibited from trading or providing services in the securities products mentioned therein prior to publication of the information.

Past performance, simulations or forecasts are not a reliable indicator of future performance. Mandatory information and limitation of liability for CapTrader and any third-party content providers can be found at https://www.captrader.com/marketingmitteilung/angaben
Please note that investing in financial instruments involves high risks and take note of our disclaimer and the mandatory legal information at the locations indicated.

  1. Mandatory information

Responsible: CapTrader GmbH, Elberfelder Straße 2, 40213 Düsseldorf; Commercial Register Number: HRB 86537 Düsseldorf Local Court; VAT ID DE323771603; Managing Directors Andreas Weiß, Christian Weiß, Michael Heyder; Tel: +49 211-740786-00, Fax: +49 211-740786-90.

Zuständige Aufsichtsbehörde: Bundesanstalt für Finanzdienstleistungsaufsicht, Graurheindorfer Straße 108, D – 53117 Bonn und Marie-Curie-Str. 24-28 D – 60439 Frankfurt am Main, Tel: 0228 4108 – 0 Fax: 0228 4108 1550 E-Mail: poststelle@bafin.de; Institutsnummer 10156708

Conflicts of interest CapTrader in marketing communications: CapTrader GmbH confirms that it does not hold any positions in the mentioned financial instruments beyond the positions mentioned in the marketing communication itself, if applicable. There are also no other conflicts of interest within the meaning of CapTrader GmbH's Financial Analysis and Marketing Communication Policy.

Conflicts of interest and mandatory disclosures by the third-party content provider for marketing communications with financial instrument recommendations: See under https://www.captrader.com/marketingmitteilung/angaben  to creators of third-party content

The copyright to the marketing communication is reserved. Reprinting and distribution is only permitted with our consent.

  1. Disclaimer

By accepting the content, the recipient accepts the binding nature of the limitation of liability.

a) Disclaimer for third-party content

CapTrader GmbH offers authors - such as editors, guest commentators, agencies and companies - the opportunity to publish comments, analyses, news and company announcements. Their opinions do not necessarily reflect the opinions and views of CapTrader GmbH and its employees. CapTrader GmbH assumes neither liability nor guarantee for this content. This applies in particular to incomplete or incorrectly reproduced reports, incorrect price information and editorial errors. Liability claims relating to material or immaterial damage caused by the use or non-use of the published information or by the use of incorrect or incomplete information are fundamentally excluded.

b) Exclusion of liability for CapTrader's own content

CapTrader has taken its own information in this marketing communication from sources believed to be reliable, but has not verified all such information itself. Accordingly, CapTrader makes no warranties or representations as to the accuracy, completeness or correctness of the information or opinions contained herein. Subsequent changes cannot be taken into account. The marketing communication does not constitute an offer or solicitation to buy shares of the issuer and is in no way a substitute for advice appropriate to the investor and the property. We cannot verify whether the information in the marketing communication is in line with your personal investment strategies and objectives. We recommend that you consult an investment advisor for advice that is appropriate to the investor and the property. The marketing communication cannot and should not replace a securities prospectus and/or expert investment advice required for an investment. It can therefore never be the sole basis for an investment decision. By accepting the marketing communication, the recipient accepts the binding nature of the above limitation of liability.

CapTrader provides the information despite careful procurement and provision only without guarantee for the correctness / completeness, timeliness or accuracy and availability of the stock exchange and economic information, prices, rates, indices, general market data, valuations, assessments and other accessible content held and displayed for retrieval. This also applies to third-party content. Historical observations and forecasts are not a reliable indicator of future developments. The facts presented in particular in connection with product information are for illustrative purposes only and do not permit any statements to be made about future profits or losses. Any conditions stated are to be understood as non-binding indications and are dependent on market developments on the day of conclusion.

CapTrader accepts no liability for any direct or indirect damage caused by and/or related to the distribution and/or use of this marketing communication.

The information, opinions and statements correspond to the status at the time of preparation of the marketing communication. They may be outdated due to future developments without the publication being changed.

CapTrader is not obliged to update, amend or supplement the information in this marketing communication if a circumstance mentioned in this publication or a statement, estimate or forecast contained therein changes or becomes inaccurate. The presentation of the performance of financial instruments over previous periods does not provide a reliable indication of their future performance. No guarantee can therefore be given for the future price, value or income of any financial instrument mentioned in this publication.

Despite careful control of the content, we assume no liability for the content of external links. The operators of the linked pages are solely responsible for their content.

Distribution: This publication may only be distributed in accordance with the laws of the respective countries, and persons in possession of this publication should inform themselves about the applicable local regulations. The information contained herein is not intended for natural or legal persons who, due to their place of residence or business, are subject to a foreign legal system that imposes restrictions on the distribution of such information. The contents are therefore exclusively in German. In particular, this publication contains neither an offer nor an invitation to purchase securities to citizens of the USA, Great Britain and Australia.

Taxes: The tax treatment of financial instruments depends on the personal circumstances of the respective investor and may be subject to future changes, which may also have a retroactive effect.

Historical observations and forecasts are not a reliable indicator of future developments. The facts presented in particular in connection with product information are for illustrative purposes only and do not permit any statements to be made about future profits or losses. Any conditions stated are to be understood as non-binding indications and are dependent on market developments on the day of conclusion.

CapTrader accepts no liability for direct or indirect damage caused by and/or in connection with the distribution and/or use.

The information, opinions and statements correspond to the status at the time of preparation of the marketing communication. They may be outdated due to future developments without the publication being changed.

CapTrader is not obliged to update, amend or supplement the information if a circumstance mentioned in this publication or a statement, estimate or forecast contained therein changes or becomes inaccurate. The presentation of the performance of financial instruments over previous periods does not provide a reliable indication of their future performance. No guarantee can therefore be given for the future price, value or income of any financial instrument mentioned in this publication.

Despite careful control of the content, we assume no liability for the content of external links. The operators of the linked pages are solely responsible for their content.

Distribution: This publication may only be distributed in accordance with the laws of the respective countries, and persons in possession of this publication should inform themselves about the applicable local regulations. The information contained herein is not intended for natural or legal persons who, due to their place of residence or business, are subject to a foreign legal system that imposes restrictions on the distribution of such information. The contents are therefore exclusively in German. In particular, this publication contains neither an offer nor an invitation to purchase securities to citizens of the USA, Great Britain and Australia.

Taxes: The tax treatment of financial instruments depends on the personal circumstances of the respective investor and may be subject to future changes, which may also have a retroactive effect.

Email:

info@captrader.com

Send e-mail

Phone:

Hotline (Germany)
0800-8723370

Hotline (International)
00800-08723370

Further contact options