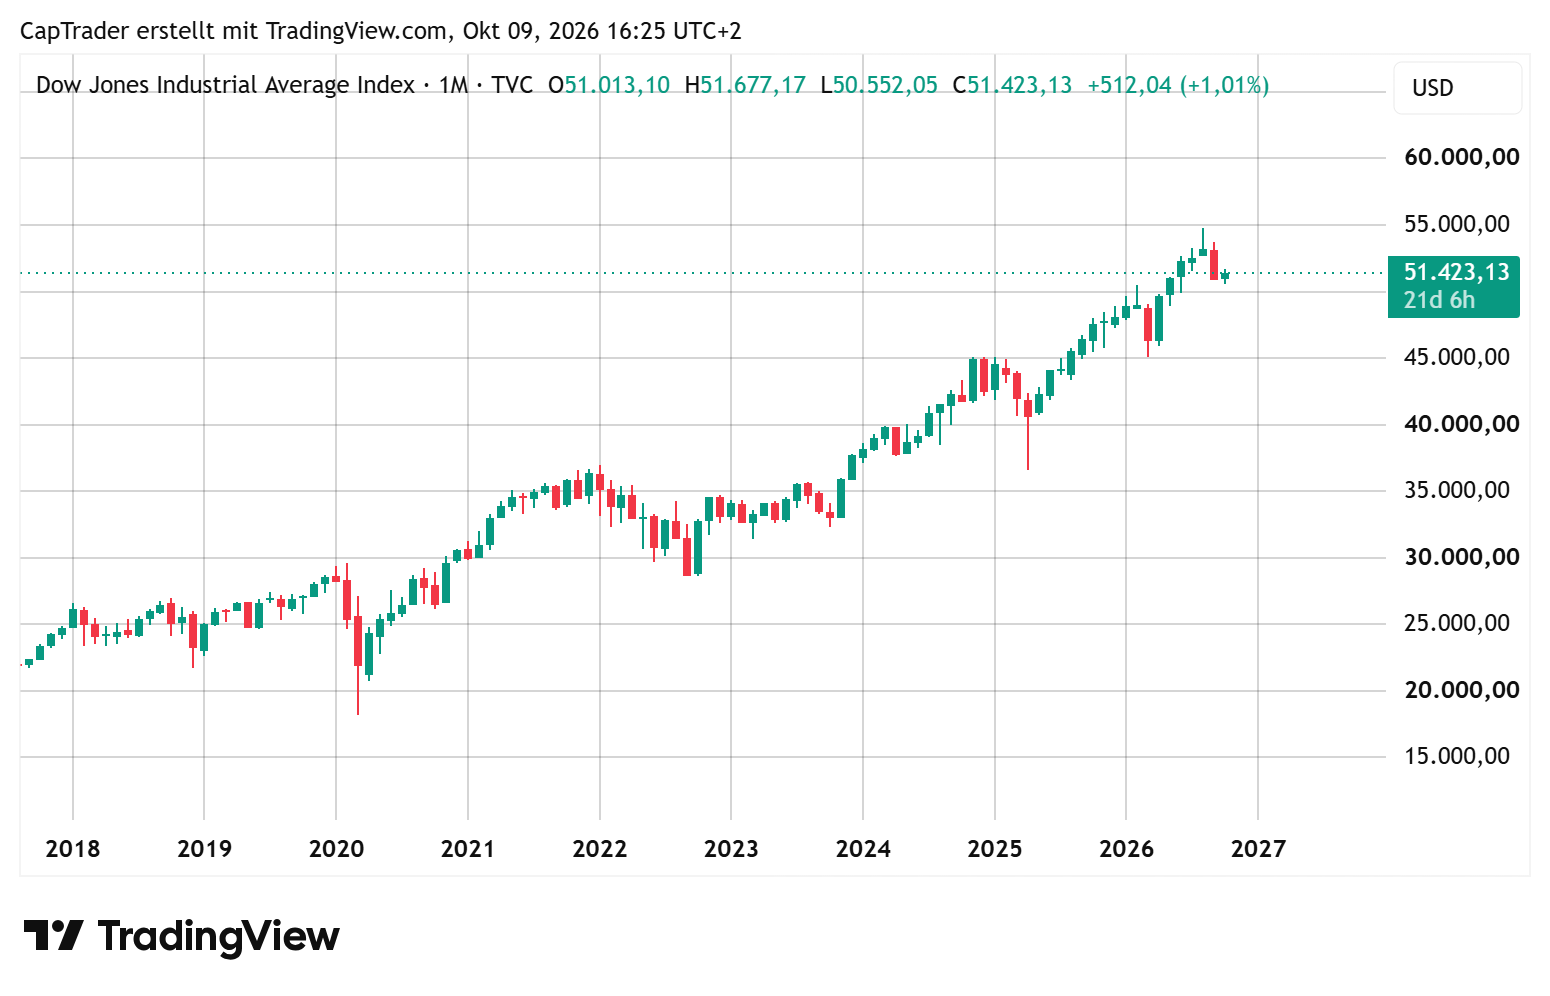
The showdown between bulls and bears is likely to continue to dominate the stock market. After the recent correction, the question remains whether the buyers can regain the upper hand again. Investors could lose their balance at any time on the tightrope between high oil prices and bond yields.
At the same time, the US reporting season is likely to further cast a shadow over the markets. Company results could soon become the most important factor influencing stock markets and mask lingering risk factors. Middle East risks, uncertainties regarding the central banks’ interest rate path, and critical questions regarding the AI sector are currently preventing the continuation of the recent record-breaking rally.
Dow Jones Industrial Average Index
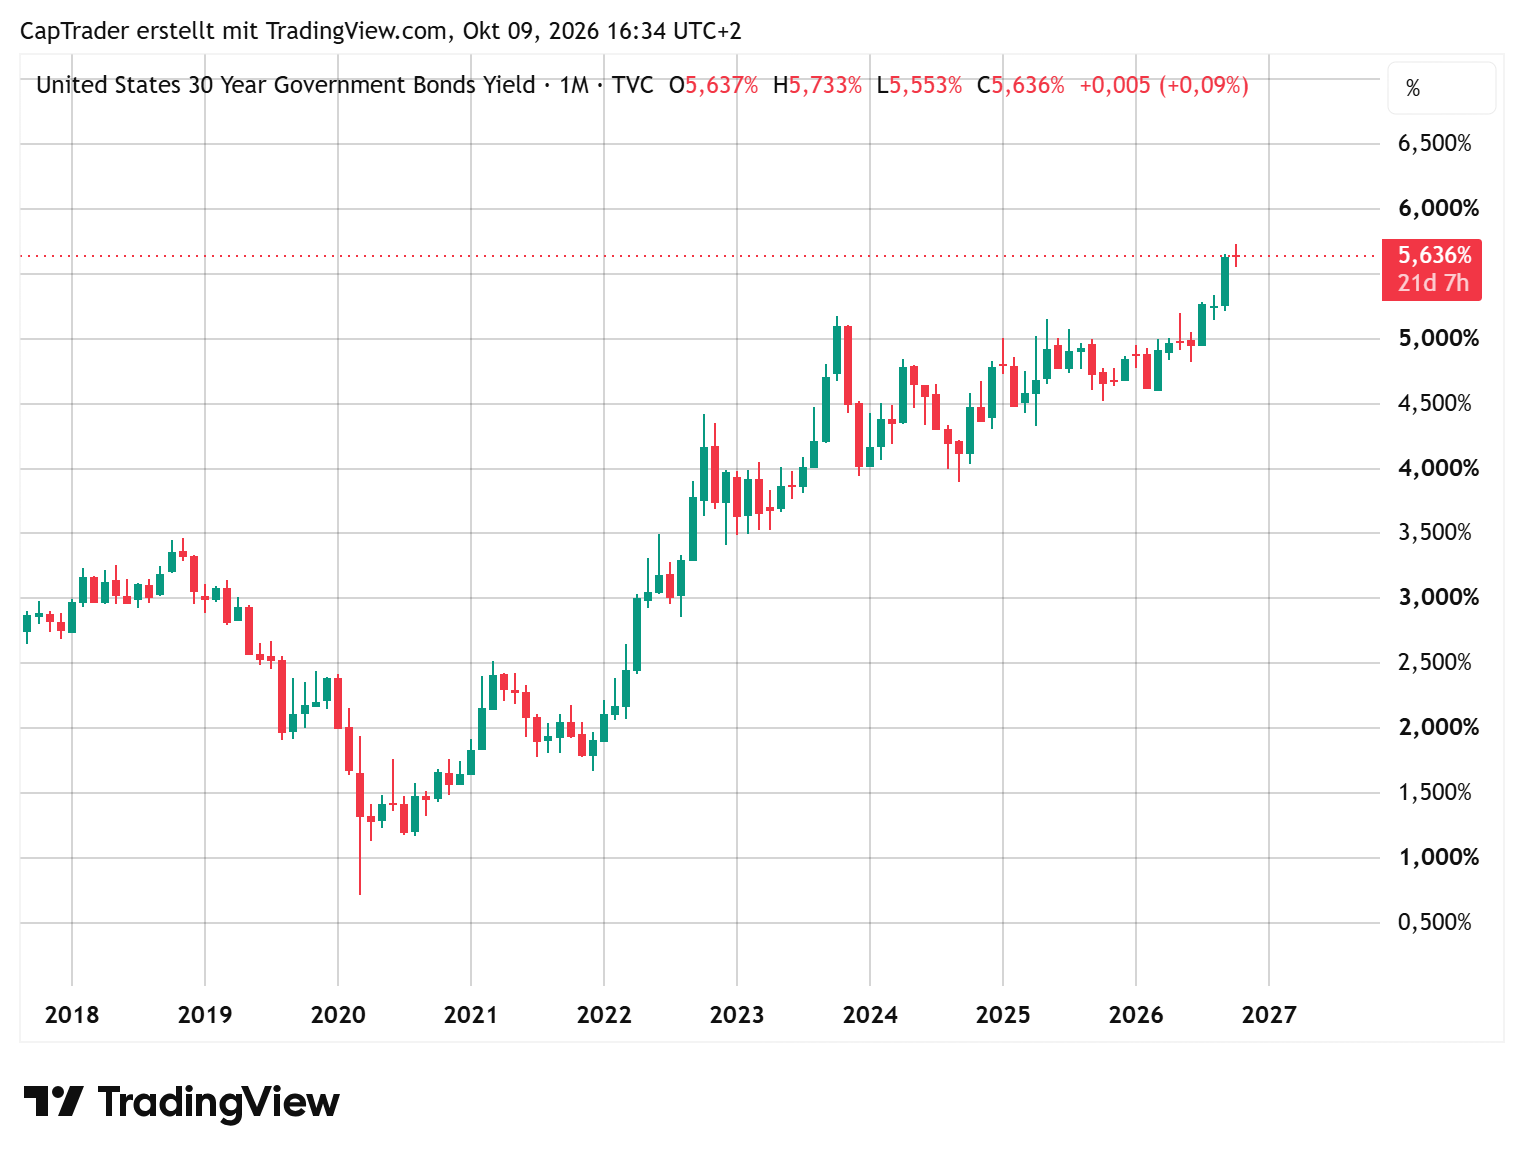
The yields of US government bonds with a maturity of 30 years last Friday reached over 5.63 percent, still the highest level since May 2002. The concern about further rising inflation and rising interest rates is likely to have contributed to this, among other things.
US government bonds (30-year maturity)
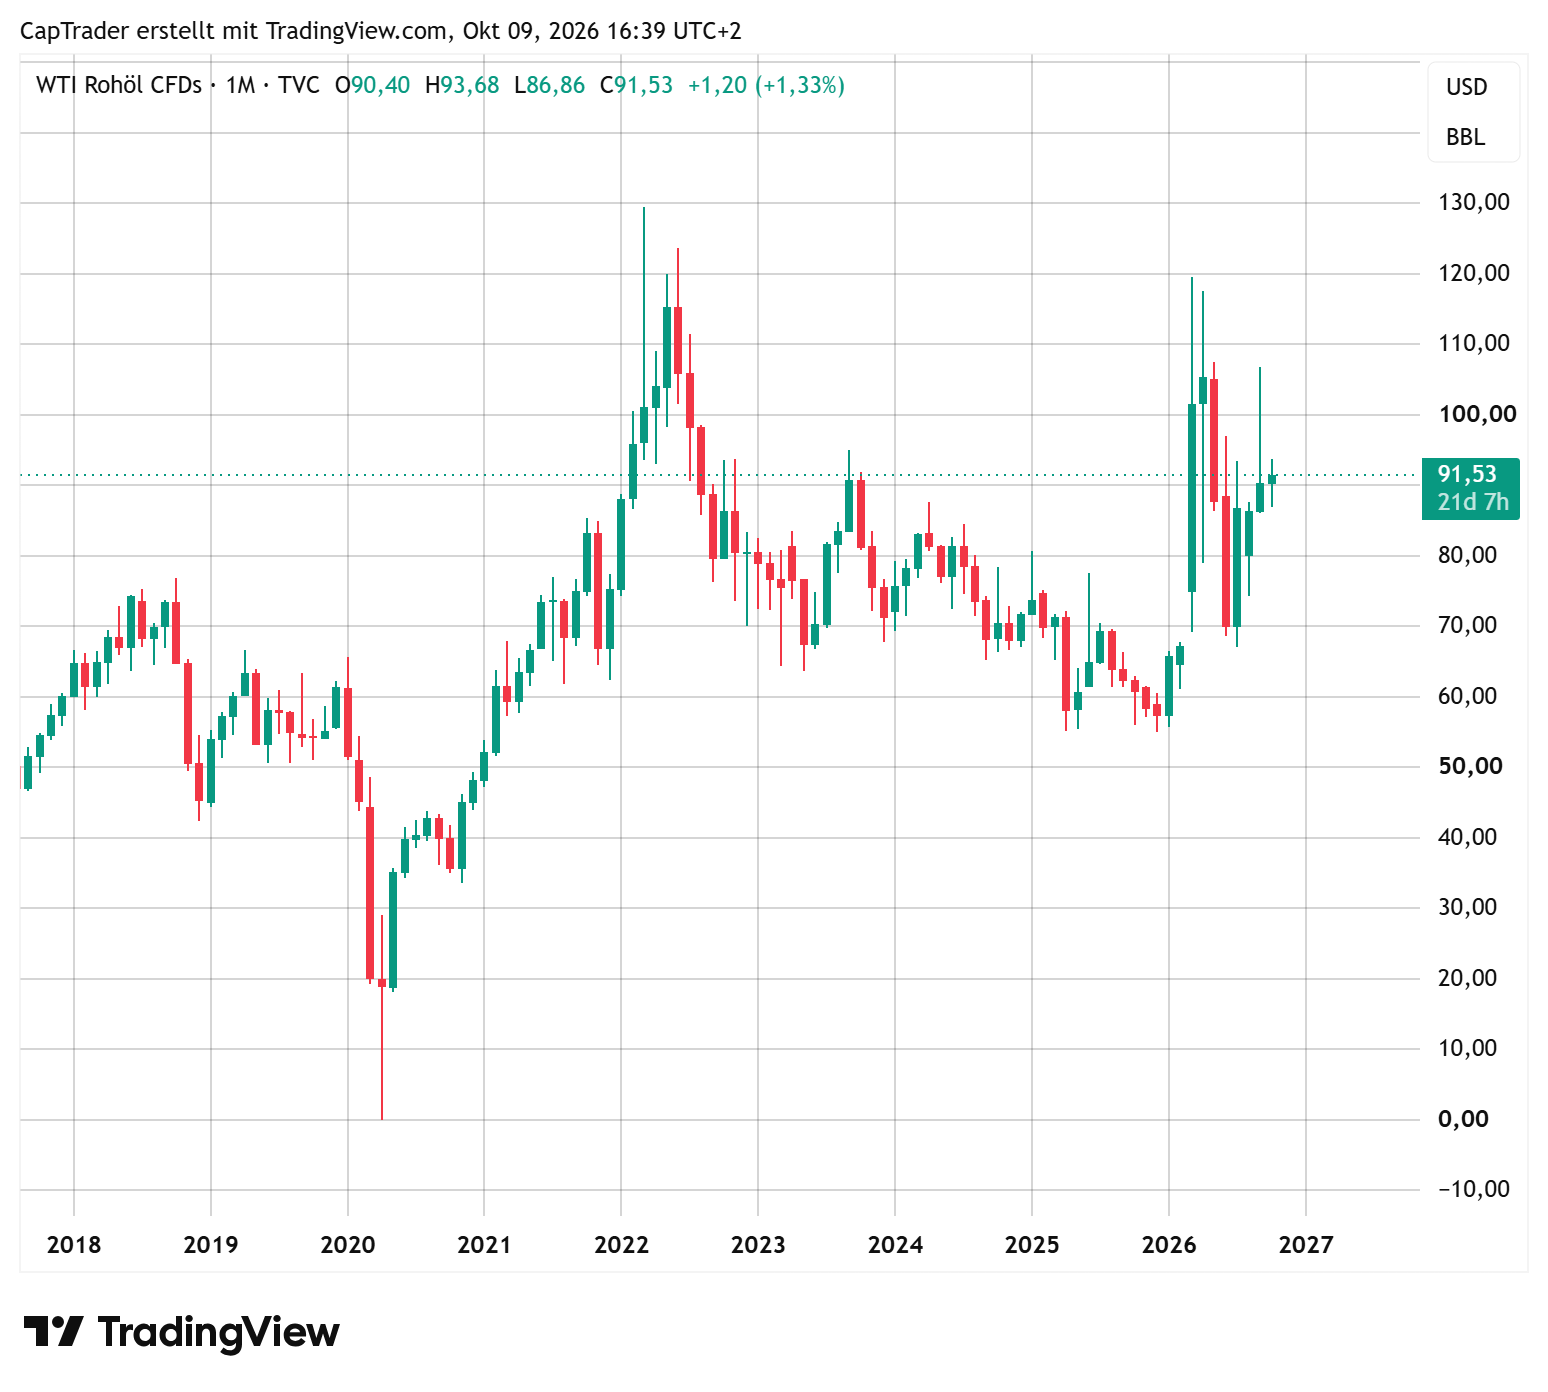
Oil price (West Texas Intermediate)
The start of the US reporting season – US inflation data is expected to send out monetary policy signals
On Tuesday, Citigroup (ISIN: US1729674242), Goldman Sachs (ISIN: US38141G1040), Johnson & Johnson (ISIN: US47816011046), JPMorgan (ISIN: US46625H1005), UnitedHealth (US91324P1021) and Wells Fargo (ISIN: US9497461015) will report on Tuesday.
On Wednesday, the figures from Bank of America (ISIN: US0605051046), BlackRock (ISIN: US09290D1019) and Morgan Stanley (ISIN: US6174464486) come into focus.
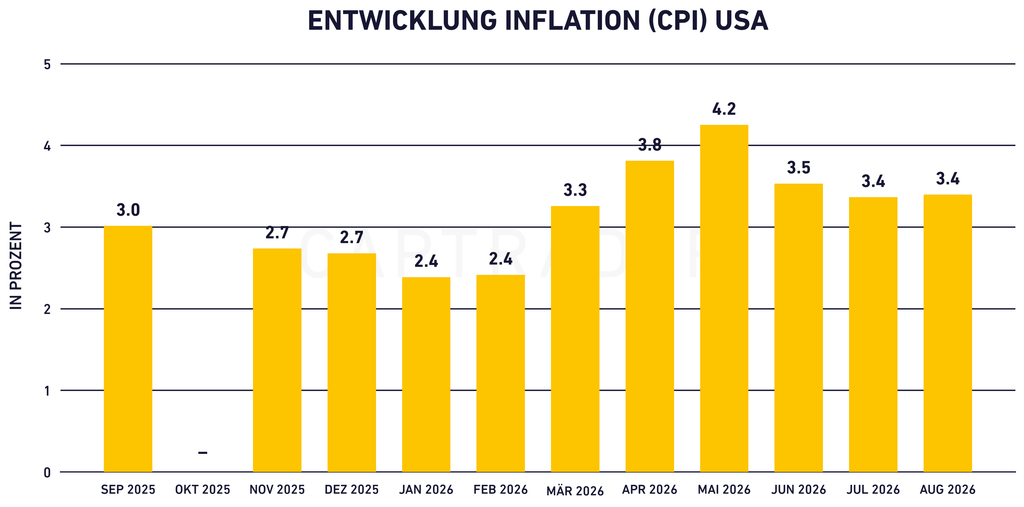
Also in focus are the inflation data for the US side, which are expected to provide important monetary policy signals. These data are expected on Wednesday at 14:30. At the same time, US producer prices are on the agenda on Thursday (14:30) and on Friday morning a speech by Fed Chairman Kevin Warsh (05:30).