Opens in a new tab
Your Broker for worldwide trading

March Analysis 2026: Crude oil, extreme volatility & bear call spreads on the VXX

Anyone who has been following the news in recent weeks could hardly fail to notice what is currently driving the markets: geopolitical escalation in the Middle East, an oil price on a rollercoaster ride and a VIX that has firmly established itself in the 25+ range. For options traders, this means stress - but also opportunity. In this March analysis, we look at precisely these three issues and show how you can use the high volatility to your advantage in a structured way: with bear call spreads on the VXX.

1. crude oil: from geopolitical shock to trade opportunity

What began at the end of February 2026 has given the commodity markets a historic shock. Coordinated airstrikes on Iranian infrastructure - by the US and Israel under the code name "Operation Midnight Hammer" - have turned the Strait of Hormuz into a crisis zone. Around 20 % of the world's oil supply flows through this maritime bottleneck every day. Since the lockdown due to sea mines and drone threats, tanker insurance has been largely suspended.

As a result, the WTI crude oil price shot up from the mid USD 60 range to over USD 100 within a few trading days - with a brief spike near USD 120. Since then, the market has calmed down somewhat: traders are taking profits and initial diplomatic signals from the White House give hope of a possible de-escalation. Nevertheless, prices remain volatile and levels remain elevated.

What does this mean for options traders? Exactly what we already mentioned in the January analysis have described: High normalized volatility makes premiums attractive - both on the side of Cash Secured Puts on equities as well as volatility strategies such as the Bear Call Spread on the VXX. However, the decisive factor is: first understand the market situation, then act.

2 The OVX: When oil volatility explodes

The OVX (CBOE Crude Oil ETF Volatility Index) is the equivalent of the VIX - only for crude oil. It measures the 30-day volatility expected by the market, based on option prices on the USO ETF (which in turn tracks the NYMEX WTI future).

In normal market phases, the OVX fluctuates between 25 and 35. Values above 50 are already considered exceptionally high - typically in phases such as the Covid crash in 2020 or the Russia-Ukraine shock in 2022. The OVX is currently trading at over 100 - a level that clearly eclipses the last 52 weeks (52-week low was 23.59).
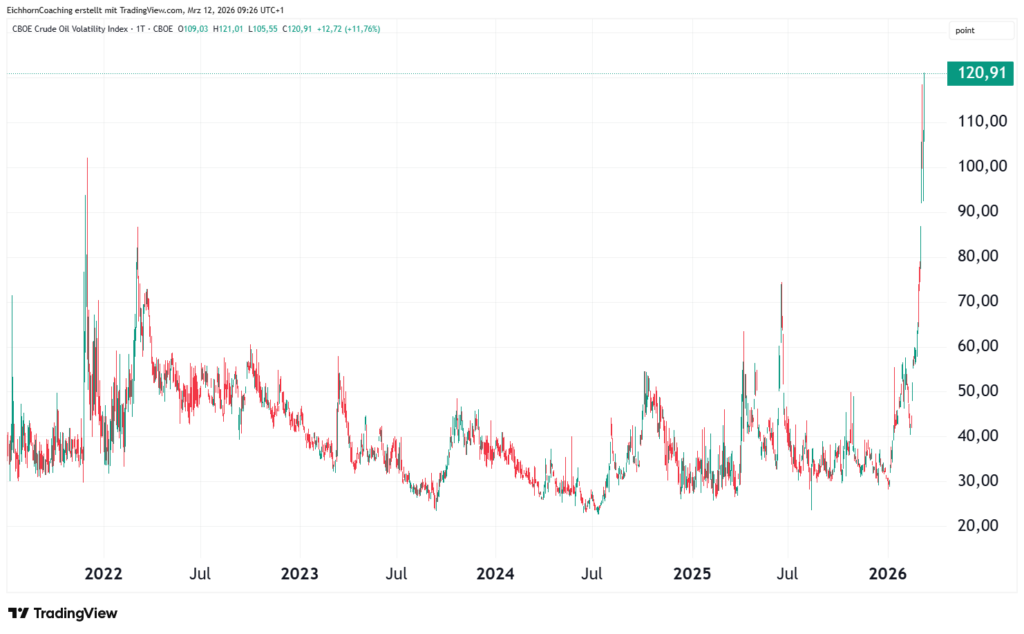
Line chart of the CBOE Crude Oil Volatility Index from 2022 to 2026, with a strong increase in 2026 to a peak value of 120.91.
Chart: Oil volatility OVX

What an OVX of 100 actually means:

  • The market expects daily price fluctuations of around 3.0-4.5 % in the price of crude oil
  • Option sellers receive extremely high premiums - but the risk is also correspondingly high
  • Directional betting on oil is very dangerous: a headline tweet can move the price by 10 % in minutes
  • Structured strategies - e.g. wide bear call spreads or butterflies on oil ETFs or VXX (more on this in a moment) - make more sense in such phases than directional trading

For option writers, the OVX above 100 is a double-edged sword. The premiums are temptingly high, but the actual risk does not justify unhedged short positions. Anyone trading here should only work with clearly defined, limited risks of loss - i.e. with spreads instead of naked options.

3. the VIX: the fear index in crisis mode

Alongside the OVX, the VIX - the classic "fear index" for the S&P 500 - has also risen significantly. After reaching an annual low of 13.38 at the end of 2025, when the market was in high spirits, the picture has changed dramatically since the beginning of March 2026.
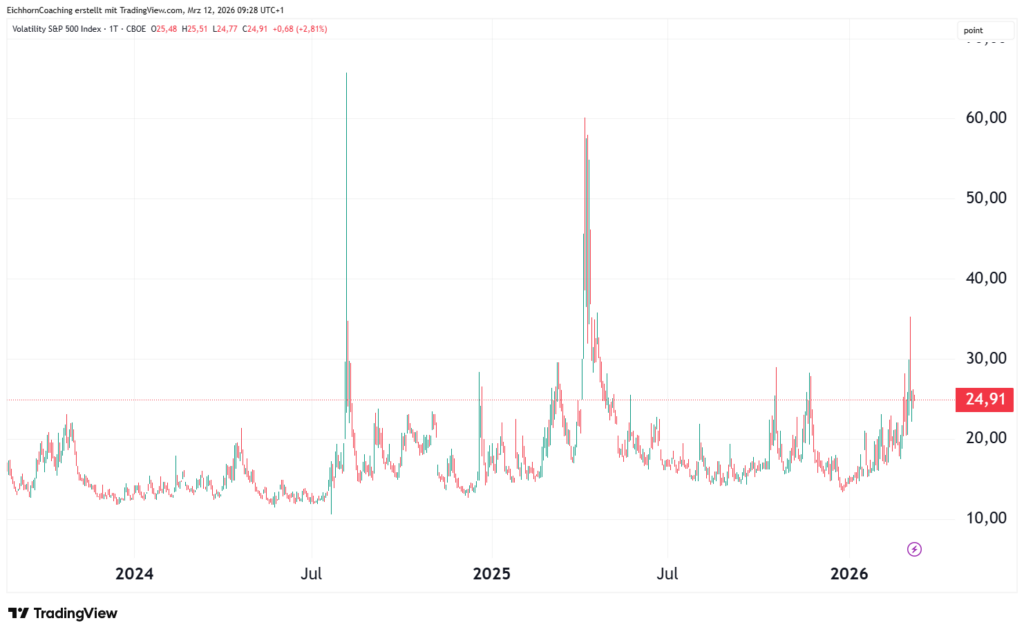
Line chart of the S&P 500 volatility index (VIX) from 2023 to 2026 with several strong swings and a final value of 24.91.
Chart: Volatility on the SPX (VIX)

The VIX is currently at around 24-26 - well above the psychological level of 25, which is seen by institutional traders as a transition to a "high volatility regime". A VIX at this level signals that the market is pricing in daily fluctuations of around 1.5 % in the S&P 500.

Three scenarios that will determine the further course of the VIX:

  • De-escalation in the Middle East: US navy secures tanker routes, Strait of Hormuz reopens → VIX decline towards 18-20 possible
  • Status quo / escalation at a low level: VIX remains in the 22-28 range, premium environment remains attractive
  • Expansion of the conflict, Iranian counterattacks on oil infrastructure → VIX spike to 35-40+ cannot be ruled out

For options traders, the middle scenario is the most interesting: a VIX that remains elevated but does not produce another spike is ideal for shorting volatility with bear call spreads. Premiums remain high and time value decay works for us.

4. short volatility with bear call spreads on the VXX

You cannot trade the VIX directly - it is only an index. But via the VXX, the iPath Series B S&P 500 VIX Short-Term Futures ETN, volatility can be traded indirectly. The VXX always holds a long position in the first two VIX futures and attempts to reflect an average term of 30 days.

The special feature of the VXX is its structural weakness over time: Because the VIX futures curve is in contango most of the time (i.e. trailing contracts are more expensive than leading contracts), systematic rolling losses occur when futures are constantly rolling. The VXX buys expensive and sells cheap - day after day. In calm market phases, the VXX continuously loses value, making it an attractive short candidate.

Important caveat: This does not apply in times of crisis with backwardation! When panic dominates the markets - as is currently the case - the VXX can rise extremely quickly and sharply. This is why you should never short the VXX naked (uncovered). The bear call spread is the smart alternative.

A bear call spread on the VXX consists of two legs:

  • Short call (sold): A call with a strike above/at the current VXX price. A premium is received.
  • Long call (bought): A call with an even higher strike. You pay a lower premium but hedge the maximum risk of loss.

The result: you receive a net premium (difference between the premium received and the premium paid), and the maximum risk of loss is limited to the distance between the strikes minus the premium.

Example trade (illustrative, not a specific trading recommendation):

  • VXX currently approx. 33
  • Term May with 64 days RLZ
  • Short call at 33 gives approx. $550 premium
  • Long call at 63 costs approx. $100
  • Maximum profit: $450
  • Maximum loss: $3,000 without premium income

Bear call spreads on the VXX should only be set up when the VIX is already high - i.e. not in quiet market phases when the VIX is below 20. The reason is simple: when the VIX is low, the VXX and VIX can still rise sharply. With a VIX of 25+, a return to normality (mean reversion) is structurally more likely, even if the timing remains unknown.

The current situation with a VIX of 24-26 and a VXX well above normal levels is a classic environment for this strategy - but with clear risk management:

  • Bear call spreads only, no naked short calls
  • Set strikes far enough out of the money to absorb short-term spikes
  • Select a position size so that a maximum loss does not seriously jeopardize the account
  • Duration not too short: 4-12 weeks give the trade time to develop
  • Actively monitor the trade: Close out early if the VIX spikes again to > 35-40

Conclusion: Crisis as an opportunity - with a clear head and limited risk

The March analysis shows once again how strongly geopolitical events can move the markets in a very short space of time. An OVX above 100 and a VIX above 25 are not an everyday occurrence - but they open a window of opportunity for options traders that does not exist in calm phases.

The tools we presented in the January analysis - cash secured puts on fallen quality stocks, coupled with monitoring social media sentiment as a contra-indicator - continue to apply. In addition, the current environment offers an attractive opportunity to profit directly from a future normalization of volatility with bear call spreads on the VXX.

The most important thing here is that limited risk is not an option, but an obligation. Anyone who trades naked short calls on a VXX at an elevated level is playing Russian roulette. The bear call spread, on the other hand, allows you to participate in the structural weakness of the VXX and the mean reversion of the VIX - with a clearly defined worst case. Discipline, patience and position management are key. As always.
THE NEXT WEBINARS WITH ALEXANDER EICHHORN AT CAPTRADER

A man with a shaved head and a short beard, wearing a black t-shirt, stands in front of a neutral gray background. He looks at the camera and smiles slightly, exuding the calm confidence often seen in experienced speakers.
Alexander Eichhorn

Alexander Eichhorn is the founder of Eichhorn Coaching and full-time trader and investor. His educational activities focus on providing optimal support for clients with large accounts. He also shows options traders how to get started quickly with profitable options trading through numerous blog articles and regularly publishes analyses and tips on the Eichhorn Coaching YouTube channel and in his monthly webinar series at CapTrader.

View all posts
Mandatory information and disclaimer

This is a marketing communication within the meaning of Section 63 (6) of the German Securities Trading Act and does not contain investment strategy recommendations, investment recommendations or financial analyses in accordance with Section 85 of the German Securities Trading Act and Article 20 of the Market Abuse Regulation. It therefore does not fulfill the legal requirements to guarantee the objectivity of investment strategy recommendations/investment recommendations/financial analyses. CapTrader GmbH or its employees are therefore not legally prohibited from trading or providing services in the securities products mentioned therein prior to publication of the information.

Past performance, simulations or forecasts are not a reliable indicator of future performance. Mandatory information and limitation of liability for CapTrader and any third-party content providers can be found at https://www.captrader.com/marketingmitteilung/angaben
Please note that investing in financial instruments involves high risks and take note of our disclaimer and the mandatory legal information at the locations indicated.

  1. Mandatory information

Responsible: CapTrader GmbH, Elberfelder Straße 2, 40213 Düsseldorf; Commercial Register Number: HRB 86537 Düsseldorf Local Court; VAT ID DE323771603; Managing Directors Andreas Weiß, Christian Weiß, Michael Heyder; Tel: +49 211-740786-00, Fax: +49 211-740786-90.

Zuständige Aufsichtsbehörde: Bundesanstalt für Finanzdienstleistungsaufsicht, Graurheindorfer Straße 108, D – 53117 Bonn und Marie-Curie-Str. 24-28 D – 60439 Frankfurt am Main, Tel: 0228 4108 – 0 Fax: 0228 4108 1550 E-Mail: poststelle@bafin.de; Institutsnummer 10156708

Conflicts of interest CapTrader in marketing communications: CapTrader GmbH confirms that it does not hold any positions in the mentioned financial instruments beyond the positions mentioned in the marketing communication itself, if applicable. There are also no other conflicts of interest within the meaning of CapTrader GmbH's Financial Analysis and Marketing Communication Policy.

Conflicts of interest and mandatory disclosures by the third-party content provider for marketing communications with financial instrument recommendations: See under https://www.captrader.com/marketingmitteilung/angaben  to creators of third-party content

The copyright to the marketing communication is reserved. Reprinting and distribution is only permitted with our consent.

  1. Disclaimer

By accepting the content, the recipient accepts the binding nature of the limitation of liability.

a) Disclaimer for third-party content

CapTrader GmbH offers authors - such as editors, guest commentators, agencies and companies - the opportunity to publish comments, analyses, news and company announcements. Their opinions do not necessarily reflect the opinions and views of CapTrader GmbH and its employees. CapTrader GmbH assumes neither liability nor guarantee for this content. This applies in particular to incomplete or incorrectly reproduced reports, incorrect price information and editorial errors. Liability claims relating to material or immaterial damage caused by the use or non-use of the published information or by the use of incorrect or incomplete information are fundamentally excluded.

b) Exclusion of liability for CapTrader's own content

CapTrader has taken its own information in this marketing communication from sources believed to be reliable, but has not verified all such information itself. Accordingly, CapTrader makes no warranties or representations as to the accuracy, completeness or correctness of the information or opinions contained herein. Subsequent changes cannot be taken into account. The marketing communication does not constitute an offer or solicitation to buy shares of the issuer and is in no way a substitute for advice appropriate to the investor and the property. We cannot verify whether the information in the marketing communication is in line with your personal investment strategies and objectives. We recommend that you consult an investment advisor for advice that is appropriate to the investor and the property. The marketing communication cannot and should not replace a securities prospectus and/or expert investment advice required for an investment. It can therefore never be the sole basis for an investment decision. By accepting the marketing communication, the recipient accepts the binding nature of the above limitation of liability.

CapTrader provides the information despite careful procurement and provision only without guarantee for the correctness / completeness, timeliness or accuracy and availability of the stock exchange and economic information, prices, rates, indices, general market data, valuations, assessments and other accessible content held and displayed for retrieval. This also applies to third-party content. Historical observations and forecasts are not a reliable indicator of future developments. The facts presented in particular in connection with product information are for illustrative purposes only and do not permit any statements to be made about future profits or losses. Any conditions stated are to be understood as non-binding indications and are dependent on market developments on the day of conclusion.

CapTrader accepts no liability for any direct or indirect damage caused by and/or related to the distribution and/or use of this marketing communication.

The information, opinions and statements correspond to the status at the time of preparation of the marketing communication. They may be outdated due to future developments without the publication being changed.

CapTrader is not obliged to update, amend or supplement the information in this marketing communication if a circumstance mentioned in this publication or a statement, estimate or forecast contained therein changes or becomes inaccurate. The presentation of the performance of financial instruments over previous periods does not provide a reliable indication of their future performance. No guarantee can therefore be given for the future price, value or income of any financial instrument mentioned in this publication.

Despite careful control of the content, we assume no liability for the content of external links. The operators of the linked pages are solely responsible for their content.

Distribution: This publication may only be distributed in accordance with the laws of the respective countries, and persons in possession of this publication should inform themselves about the applicable local regulations. The information contained herein is not intended for natural or legal persons who, due to their place of residence or business, are subject to a foreign legal system that imposes restrictions on the distribution of such information. The contents are therefore exclusively in German. In particular, this publication contains neither an offer nor an invitation to purchase securities to citizens of the USA, Great Britain and Australia.

Taxes: The tax treatment of financial instruments depends on the personal circumstances of the respective investor and may be subject to future changes, which may also have a retroactive effect.

Historical observations and forecasts are not a reliable indicator of future developments. The facts presented in particular in connection with product information are for illustrative purposes only and do not permit any statements to be made about future profits or losses. Any conditions stated are to be understood as non-binding indications and are dependent on market developments on the day of conclusion.

CapTrader accepts no liability for direct or indirect damage caused by and/or in connection with the distribution and/or use.

The information, opinions and statements correspond to the status at the time of preparation of the marketing communication. They may be outdated due to future developments without the publication being changed.

CapTrader is not obliged to update, amend or supplement the information if a circumstance mentioned in this publication or a statement, estimate or forecast contained therein changes or becomes inaccurate. The presentation of the performance of financial instruments over previous periods does not provide a reliable indication of their future performance. No guarantee can therefore be given for the future price, value or income of any financial instrument mentioned in this publication.

Despite careful control of the content, we assume no liability for the content of external links. The operators of the linked pages are solely responsible for their content.

Distribution: This publication may only be distributed in accordance with the laws of the respective countries, and persons in possession of this publication should inform themselves about the applicable local regulations. The information contained herein is not intended for natural or legal persons who, due to their place of residence or business, are subject to a foreign legal system that imposes restrictions on the distribution of such information. The contents are therefore exclusively in German. In particular, this publication contains neither an offer nor an invitation to purchase securities to citizens of the USA, Great Britain and Australia.

Taxes: The tax treatment of financial instruments depends on the personal circumstances of the respective investor and may be subject to future changes, which may also have a retroactive effect.

Email:

info@captrader.com

Send e-mail

Phone:

Hotline (Germany)
0800-8723370

Hotline (International)
00800-08723370

Further contact options